
Insurance guides
Protect Your Manufactured Home in San Marcos, TX.
Disclaimer: Data Accuracy and Sources
The data in the Covertree Resources section is from publicly available sources last updated in December 2022. We provide source links for verification. However, we can’t guarantee accuracy. Rely on this data at your own discretion. For specific advice, consult professionals.
Welcome to San Marcos, Texas -a gem of natural beauty and ancient mysteries in the Texas Hill Country!
Nestled between the bustling urban centers of Austin and San Antonio, San Marcos emerges as a captivating blend of natural wonders, ancient history, and a lively contemporary scene. With the shimmering San Marcos River at its heart, this Texas Hill Country city offers a treasure trove of experiences that both soothe the soul and stir the imagination.
The story of San Marcos is as old as time itself. Archaeological finds indicate that the area has been continuously inhabited for over 10,000 years, making it among the oldest known inhabited sites in the Americas. This rich tapestry of human history is beautifully showcased at sites such as the Meadows Center for Water and the Environment, where glass-bottom boat tours provide glimpses into the clear springs and underwater archaeological treasures.
The San Marcos River, spring-fed and crystal clear, is undeniably the lifeblood of the city. It meanders gently through town, providing both scenic beauty and a hub for countless recreational activities. Tubing down its gentle currents is a rite of passage for many, while others might prefer kayaking, snorkeling, or simply basking by its banks, letting the world drift by. Beyond the river’s allure, San Marcos boasts a vibrant arts and cultural scene. The city is home to Texas State University, and with it comes a pulsating energy of youth, creativity, and innovation. This academic influence infuses the city with cultural events, theater performances, and music festivals.
Shopping enthusiasts have long revered San Marcos for its expansive outlet malls, which rank among the largest in the United States. But beyond these retail giants lies a charming downtown district, with local boutiques, antique shops, and eateries offering a more intimate shopping experience.
Nature lovers find solace in places like the Purgatory Creek Natural Area, a sprawling preserve with trails meandering through diverse ecosystems, offering glimpses of the region’s flora and fauna. The Wonder World Park, a unique Texas State Historical Site, features an earthquake-formed cave and offers an intriguing exploration of the subterranean world.
One of the city’s lesser-known treasures is its commitment to preserving endangered species. The San Marcos Aquatic Resources Center is at the forefront of efforts to protect and rehabilitate species native to the springs and waterways of the region.
San Marcos’s culinary scene is as diverse as its history. From authentic Tex-Mex delights to innovative global fusion, the city’s eateries are a testament to its rich cultural influences and innovative spirit.
In essence, San Marcos is where ancient springs whisper tales from millennia past, where verdant landscapes beckon, and where the vibrancy of modern life unfolds against a backdrop of timeless beauty. Whether drawn by its historical mysteries, natural allure, academic vigor, or cultural tapestry, visitors to San Marcos are promised an encounter with the enchanting heart of the Texas Hill Country.
Understanding Mobile Home Insurance In Texas.
Do I Need Mobile Home Insurance in Texas?
Do I Need Mobile Home Insurance in Texas?
- Optional, but often required by lenders and mobile home communities.
- Lenders can’t mandate coverage that surpasses home and content replacement value.
- Strongly recommended for financial protection against damages.
Texas Mobile Home Insurance Costs Explained
Texas Mobile Home Insurance Costs Explained
Mobile home insurance is essential for safeguarding your most valuable asset. Prices in Texas typically range from $250 to $1,300 annually, influenced by various factors. Deciding between actual cash value and replacement cost coverage will also impact both premiums and compensation amounts in case of a claim.
Insurance rates are influenced by:
Insurance rates are influenced by:
- Geographic area (land value, crime rate, and environmental threats).
- Home’s value, size, and location.
- Home’s age.
- Chosen liability coverage.
- Desired personal property coverage amount.
- Selected deductible.
- Actual Cash Value: Compensates the current value of the home, accounting for depreciation. *
- Replacement Cost: Covers the cost of a new, similar home regardless of the original home’s age or previous value. **
* e.g. A five-year-old home bought for $50,000 but now worth $35,000 will be compensated at $35,000.
** Typically has higher premiums but offers more compensation during a claim.
Unique Considerations for Texas Mobile Home Insurance!
Unique Considerations for Texas Mobile Home Insurance!
- Wind and hail coverage may be excluded for homes near the coast.
- Purchase flood insurance via the National Flood Insurance Program if difficult to find in the private market.
- For wind and hail coverage, consider Texas Windstorm Insurance Association (TWIA).
Mobile Home Insurance Coverage in Texas:
Mobile Home Insurance Coverage in Texas:
- Dwelling coverage: Protection for permanent structures attached to the home.
- Personal property: Covers belongings if damaged or stolen.
- Liability protection: Provides financial protection in case a guest is injured on your property.
- Other structures: Coverage for free-standing structures on your property, e.g., sheds or fences.
- Additional living expenses: Covers costs if home becomes uninhabitable due to a covered loss.
Filing a Mobile Home Insurance Claim in Texas:
Filing a Mobile Home Insurance Claim in Texas:
- Insurance companies must acknowledge the claim within 15 days.
- Companies have 15 business days to accept or deny a claim, with potential for extensions in the event of major disasters.
- Possible 45-day decision timeframe if reasons are provided for delay.
- Failure to adhere to deadlines could result in the company being sued for the claim amount, interest, and legal fees.
Tips for Purchasing Mobile Home Insurance in Texas:
Tips for Purchasing Mobile Home Insurance in Texas:
- Mobile home insurance is often pricier than standard homeowners insurance.
- Best way to get affordable rates is to compare quotes from various companies.
- Online quotes might not be available; be prepared to call companies.
- Customizable policy options available to cater to individual needs.
Remember, while insurance might seem optional, it provides invaluable peace of mind against potential financial setbacks.
Choosing the Ideal Texas Homeowners Insurance Policy:
Choosing the Ideal Texas Homeowners Insurance Policy:
The apt insurance policy largely hinges on your home type, repair or rebuilding costs, and the worth of your belongings. It’s often a smart move to opt for the most robust protection within your budget. This is especially true if you haven’t set aside a significant emergency fund. Though a comprehensive policy with a lower deductible might require higher premiums, it ensures quick recovery after a substantial loss.
As your savings grow, you might consider increasing your deductible to decrease your premium. But here’s a pro tip: sometimes, a $1,000 deductible isn’t much pricier than a $5,000 one. In such instances, the minimal extra expense can prove invaluable in the event of a large claim.
The location of your mobile home, particularly the zip code in Texas, is a significant factor.
The location of your mobile home, particularly the zip code in Texas, is a significant factor.
You Need: The HO-7: Texas Mobile Home Form
You Need: The HO-7: Texas Mobile Home Form
- For Texas residents who own a mobile home, the HO-7 insurance form is crucial.
- This insurance covers both your dwelling and personal property.
- The HO-7 offers comparable coverage to the HO-3 policy.
- One thing to remember: if you plan on moving your mobile home, the HO-7 doesn’t always cover it while in transit. You may need to consider supplemental insurance in such cases.
What Does an HO-7 Policy Cover?
Type of Homes: Mobile or manufactured homes (trailers, single/double-wide mobile homes, RVs, modular homes, etc.).
Property (Dwelling & Other Structures)
Contents (Personal Property)
Dwelling & Other Structures
Personal Property
Valuable Items
Liability
Loss of Use
Medical Payments
What Does an HO-7 Policy NOT Cover?
Personal property damage that doesn't fit the named perils. Exclusions include:
- Floods
- Hurricanes
- Mold (Limited Coverage Might be Possible to Add)
- Earthquakes (Separate Policy Might be Available)
- Vandalism to Vacant Dwellings
- Wear and Tear
- Damage From Pets
- Intentional Acts
- Neglect
- Government Actions
Understand The HO-3: Texas Special Form
The HO-3 policy is the predominant homeowners insurance in Texas. It offers open-peril coverage for homes and related structures, covering all damages unless specifically excluded. Exclusions typically include:
- Earthquakes
- Floods
- Damage from insects & vermin
- Wear, neglect, or intentional damage
- Wind/hail damage to trees
- Vacancies, continuous water leaks
- Sewer backups, acts of war
- Certain mold cases
Additional Insurance Policy Options:
Even if you’ve chosen the HO-7 or another base form for your policy, you might still want to contemplate additional coverage for specific scenarios. Here are some prevalent options:
Texas DP-1 Insurance
Texas DP-3 Insurance
Personal Umbrella Policy
Scheduled Personal Property Coverage
Water Backup Coverage
Unmitigated Disasters
Choosing the Right Mobile Home Insurance for San Marcos, TX.
Tornado Risk
The tornado index places San Marcos at 170.75, suggesting a heightened tornado risk compared to the U.S. average but slightly less than the Texas state average.
Comparative Index: The U.S. average tornado index is 136.45, and the Texas average stands at 208.58. This means San Marcos's tornado risk is approximately 25% higher than the national average.
While it's below the state average, it's crucial to remember Texas is one of the more tornado-prone states, and thus San Marcos's risk is still significant on a broader scale.
Flood Risk
San Marcos stands prominently exposed to flood risks, with 3,111 properties identified to have a major flood threat over the next 30 years. This equates to an alarming 32% of all properties in the city.
Residential Properties: Out of 9,800 homes, 3,248 (or 33%) face a major flood risk. This suggests that one in every three homes has a significant chance of flooding, which could result in property damage, displacement, or loss of valuables.
Roads: 184 miles of the total 400 miles of roads in San Marcos, or 46%, are at a major risk of flooding. Such roads can become impassable, disrupting travel and posing potential dangers to drivers unfamiliar with the area.
Commercial Properties: San Marcos has 349 out of 844 commercial properties at a severe flood risk. This is 41% of all commercial entities, indicating a substantial threat to the local economy, job security, and business continuity.
Social Facilities: These serve as the backbone for community gatherings, educational activities, and social interactions. 15 out of 51 social facilities, or 29%, face severe flood risks, which could disrupt community services and events.
Heat Risk
San Marcos faces a severe risk from increasing temperatures. The entire residential zone, constituting 100% of homes, is under a Severe Heat Factor.
Heat Distribution: Remarkably, out of the total properties in San Marcos, 14,254 are at risk due to heat. The severe category alone encompasses 14,300 properties, while one property falls under the extreme category. This suggests that nearly every home in San Marcos faces the challenges of intense heat, which can affect residents' health, increase energy bills, and strain local energy resources.
We do insurance better. And here’s how.
- Save an average of $250 per year
- File a claim in 3 minutes
- Easily manage your policy online
- Skip the faxing, long paperwork, and unnecessary phone calls
- Get support from an American-based team
Are you in San Marcos, TX, looking for mobile home insurance
Choice of 6 insurance coverage in San Marcos, TX.
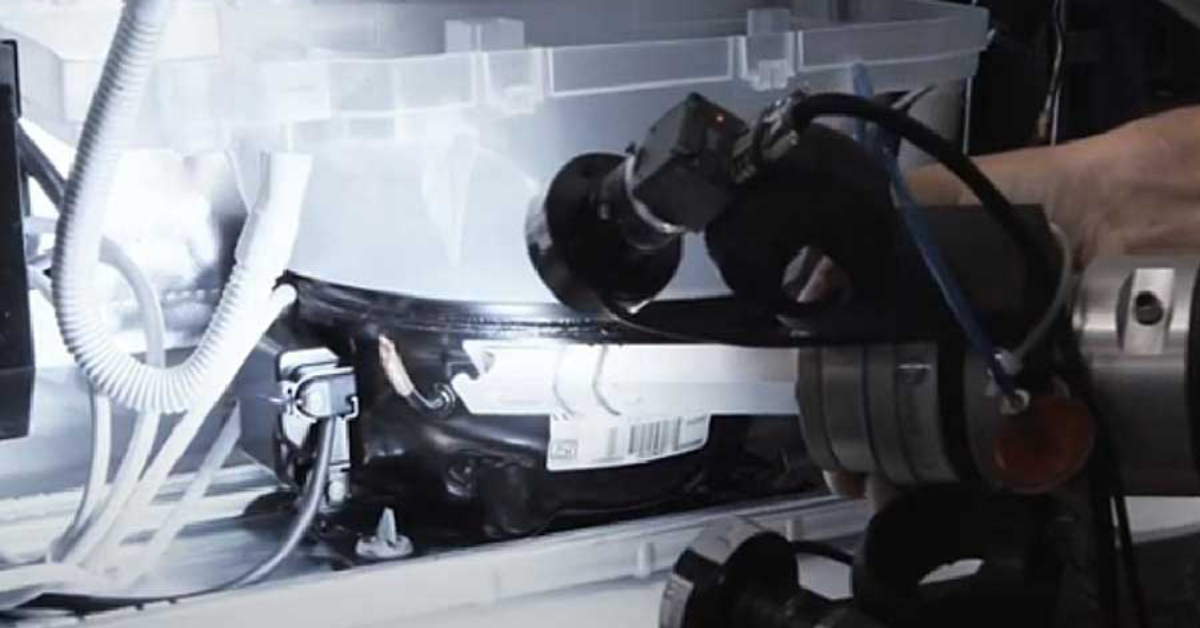
Appliance Leakage
What it is: Coverage for damages specifically caused by leaks from appliances.
Why it's needed: Appliances can sometimes malfunction, leading to expensive water damages.
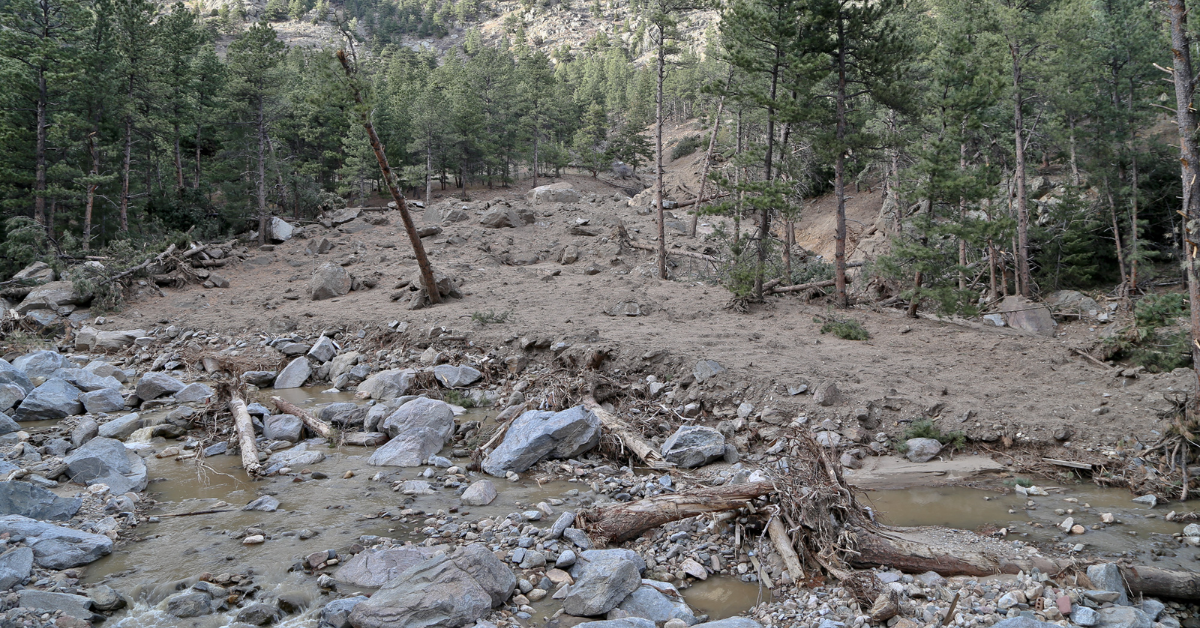
Mudflow Protection
What it is: Protection against damage caused by mudflow.
Why it's needed: In areas prone to heavy rains or near mountains, mudflows can pose a significant risk.
Windstorm and Hail Coverage
What it is: Protects against damages from windstorms and hail.
Why it's needed: Especially vital in regions prone to strong winds or frequent hailstorms.
Business Property
What it is: Extends coverage to business property stored or used in the home.
Why it's needed: For those who run a home-based business or store business items at home, it ensures they're financially protected.
Replacement Cost
What it is: Compensates the homeowner for the full, current cost of replacing damaged property without factoring in depreciation.
Why it's needed: Ensures that in the event of a loss, the homeowner can replace items without incurring out-of-pocket expenses due to depreciation.
Equipment Breakdown
What it is: Coverage for the cost of repairing or replacing household appliances after mechanical or electrical failures.
Why it's needed: Household appliances are essential and can be expensive to repair or replace. This coverage minimizes those costs.
Mobile Home Facts : Texas
Treatment of Manufactured Home as Real Property:
- Once a “real property election” for a manufactured home is completed, the home is deemed as real property.
- This status remains unless the home is moved, the election changes, or the property’s use alters.
- Once a statement of ownership and location is given by the department, it’s final. Changes can only be made if all parties agree, or specific procedures are followed.
- If taking responsibility for a Statement of Ownership, ensure all housing department steps are followed, including necessary notifications.
According to the Texas Underwriting Manual TX: 12.24:
- 12.24.3: Any manufactured housing unit on the property isn’t included in the land described in this commitment or policy.
- 12.24.4: Upon a lender’s request and payment as specified in R-11(e), the T-31 and/or T-31.1 Endorsements can be issued; T-31.1 can be given to both the owner and the lender.
Learn about Texas Homeowner Assistance: Two Vital Programs!
Texas residents who are struggling with home-related expenses have two vital assistance programs available: the Texas Homeowner Assistance Program due to the COVID-19 pandemic and the Homeowner Assistance Program (HAP) following Hurricane Harvey.
Treatment of Manufactured Home as Real Property:
Purpose: Support homeowners impacted by Hurricane Harvey to repair, rebuild, and enhance their homes.
Services Offered: Financial support for affected homeowners.
Homeowner Assistance Program (HAP):
Purpose: Support homeowners impacted by Hurricane Harvey to repair, rebuild, and enhance their homes.
Services Offered: Home repairs and rehabilitation I Home reconstruction I Enhancements for better resilience against natural disasters I Elevating homes above flood levels along with reconstruction aid I Temporary relocation aid
Residents are encouraged to assess their eligibility and take advantage of these programs to secure and improve their homes.
The Texas Coastal Insurance Pool (TCIP), formerly known as the Texas Windstorm Insurance Association (TWIA), is a vital insurance entity designed to protect homeowners in the Texas coastal regions. Established in the face of limited private insurance options, the TCIP provides wind and hail coverage to properties located in certain parts of Texas’s seacoast territory.
Texas Coastal Property Insurance Pool Programs!
Key Features:
Rates:
Inland of the Intracoastal Canal $2.50 per $100 coverage 42 Effective October 1, 2008 Seaward of the Intracoastal Canal $5.00 per $100 coverage
Eligibility for TWIA:
A mobile home located in a designated catastrophe area that meets the following criteria is eligible to be insured under the T.W.I.A. Dwelling Policy with Form No. TWIA-411, Conversion to TWIA Manufactured Home Policy attached to the policy.
The mobile home complies with the definition of manufactured home under the rules and regulations of the Texas Department of Housing and Community Affairs (TDHCA). Criteria 2 The mobile home is occupied solely as a one or two family residence. Criteria 3Additions to Mobile Homes:
- A site-built addition attached to a mobile home will rate as part of the mobile home.
- A building certification from the Texas Department of Insurance is required for the site-built addition.
- Separate structures (not physically attached to the mobile home) are not eligible for insurance under the T.W.I.A. Dwelling Policy with Form No. TWIA411, Conversion to TWIA Manufactured Home Policy attached to the policy. Refer to eligibility requirements for insurance under the Association’s Dwelling Policy.
Deductibles:
- The following deductibles are mandatory under the T.W.I.A. Dwelling Policy with Form No. TWIA-411, Conversion to TWIA Manufactured Home Policy attached to the policy. a. Homes located inland of the Intracoastal Canal: 1% of limit of liability with a $250 minimum (TWIA Form No. 570) b. Homes located seaward of the Intracoastal Canal: 2% of the limit of liability with a $250 minimum (TWIA Form No. 575)
- Deductibles apply separately to the home and household goods items on the policy.
Limit of Liability:
The maximum limit of liability for a mobile home, including any site-built additions attached to the home, and household goods is $84,000.
Policy Forms & Endorsements:
The following policy form is to be used: T.W.I.A. Dwelling Policy with Form No. TWIA-411, Conversion to TWIA Manufactured Home Policy attached to the policy
Know Your Rights!
- Texas Tenant Advisor
- Texas Law Help – Manufactured Housing Owner’s Rights
- Property Code TITLE 8. Landlord and Tenant Chapter 94. Manufactured Home Tenancies
- Property Code TITLE 8. Landlord and Tenant Chapter 92. Manufactured Home Tenancies
- Landlords and Tenants Guide for Manufactured Home Communities
- Texas Manufactured Housing Standards Act
- Legal Q&A By Sarah Tompkins, TML Legal Counsel
- Texas Law Help – What To Know Before You Buy a Manufactured/Mobile Home
- Homeowner Assistance Program
- Manufactured Housing Single-Trip Permits
- Mobile Home Insurance in Texas
- Texas Department of Insurance – Consumer Guides: Homeowner’s Insurance Guide
- Consumer Bill of Rights
- Texas Windstorm Insurance Association
- Texas Windstorm Help Guide
- Texas Law Help – Manufactured Housing and Disasters
Additional Policy Riders for Mobile Home Insurance in Texas:
Adding policy options to a basic insurance plan is a common practice in the mobile home insurance industry. While the events covered in mobile home policies are similar across all states, additional coverage options, known as add-ons, endorsements, and riders, may vary depending on your location and insurance provider. Each of these options comes at an additional cost that can be customized according to your needs.
Provides protection against flood-related damages, excluding waterline or sewer backups. Average annual cost: $700. Earthquake InsuranceAdding any rider will increase your premiums, influenced by location, risk profile, chosen coverage, and deductible. Riders can be added during initial policy purchase, at renewal, or anytime during the policy period. Some carriers might not offer all endorsements, so shopping around might be necessary.