
Insurance guides
Protect Your Manufactured Home in Georgetown, TX.
Disclaimer: Data Accuracy and Sources
The data in the Covertree Resources section is from publicly available sources last updated in December 2022. We provide source links for verification. However, we can’t guarantee accuracy. Rely on this data at your own discretion. For specific advice, consult professionals.
Welcome to Georgetown, Texas -a historic gem in the heart of the Lone Star State! Tucked away in the picturesque Hill Country of central Texas, Georgetown stands as a beacon of history, charm, and Southern hospitality. Rich in heritage and wrapped in an aura of nostalgia, the city is more than just a dot on the map—it’s a testament to the enduring spirit of Texan culture and a haven for those seeking to connect with the roots of the state.
The history of Georgetown can be traced back to the early 19th century. The area was originally inhabited by the Tonkawa Native American tribes, followed by the Comanches and Lipan Apaches who made frequent incursions. In 1848, the city was founded by European settlers, and by 1849, it was chosen as the Williamson County seat due to its central location. Named in honor of George Washington Glasscock, who donated the land for the town, Georgetown quickly became the hub of economic and cultural activities in the region.
One significant moment in its timeline was the arrival of the railroad in the 1870s. This transportation revolution turned Georgetown into a nexus of trade and commerce, bringing with it prosperity and growth. The discovery of mineral springs also earned the town the moniker “Health Resort of Texas” in the late 19th century.
Beyond its historical essence, Georgetown has always been a city of progress. It is known as the “Red Poppy Capital of Texas” because of the vibrant wildflowers that blanket its landscape every spring. These red poppies, introduced by a soldier returning from World War I, now serve as an emblem of the city’s resilience and beauty.
In recent years, Georgetown gained recognition for its commitment to renewable energy. As of 2018, it became one of the largest cities in the U.S. to be powered by 100% renewable energy—a milestone that underlines its forward-thinking ethos. Often regarded as the “Most Beautiful Town Square in Texas,” Georgetown’s downtown is lined with Victorian-era storefronts, local boutiques, and charming cafes. A stroll here is akin to taking a step back in time.
The Inner Space Cavern, discovered in the 1960s, is an underground cave that is a natural wonder, brimming with stalactites, stalagmites, and hidden passages. The Blue Hole, a scenic lagoon on the South San Gabriel River, is an oasis for locals and visitors alike, offering picturesque spots for picnics and relaxation. The Georgetown Art Center & The Palace Theatre are must-visit spots for art enthusiasts, showcasing the city’s commitment to promoting arts and culture. The Annual Red Poppy Festival, held every spring, celebrates the iconic wildflower with parades, live music, crafts, and food.
Some other interesting facts about Georgetown include:
Georgetown’s historic district boasts more than 180 homes and buildings listed on the National Register of Historic Places.
The city has been a filming location for several movies, including the 2003 film “Secondhand Lions.”
Southwestern University, located in Georgetown, is the oldest university in Texas, founded in 1840.
Georgetown is more than just a city; it’s a living narrative of Texan legacy. It’s where history meets modernity, where tradition blends with innovation. Whether you’re a history buff, an adventure enthusiast, or someone seeking serenity, Georgetown has a chapter waiting just for you.
Understanding Mobile Home Insurance In Texas.
Do I Need Mobile Home Insurance in Texas?
Do I Need Mobile Home Insurance in Texas?
- Optional, but often required by lenders and mobile home communities.
- Lenders can’t mandate coverage that surpasses home and content replacement value.
- Strongly recommended for financial protection against damages.
Texas Mobile Home Insurance Costs Explained
Texas Mobile Home Insurance Costs Explained
Mobile home insurance is essential for safeguarding your most valuable asset. Prices in Texas typically range from $250 to $1,300 annually, influenced by various factors. Deciding between actual cash value and replacement cost coverage will also impact both premiums and compensation amounts in case of a claim.
Insurance rates are influenced by:
Insurance rates are influenced by:
- Geographic area (land value, crime rate, and environmental threats).
- Home’s value, size, and location.
- Home’s age.
- Chosen liability coverage.
- Desired personal property coverage amount.
- Selected deductible.
- Actual Cash Value: Compensates the current value of the home, accounting for depreciation. *
- Replacement Cost: Covers the cost of a new, similar home regardless of the original home’s age or previous value. **
* e.g. A five-year-old home bought for $50,000 but now worth $35,000 will be compensated at $35,000.
** Typically has higher premiums but offers more compensation during a claim.
Unique Considerations for Texas Mobile Home Insurance!
Unique Considerations for Texas Mobile Home Insurance!
- Wind and hail coverage may be excluded for homes near the coast.
- Purchase flood insurance via the National Flood Insurance Program if difficult to find in the private market.
- For wind and hail coverage, consider Texas Windstorm Insurance Association (TWIA).
Mobile Home Insurance Coverage in Texas:
Mobile Home Insurance Coverage in Texas:
- Dwelling coverage: Protection for permanent structures attached to the home.
- Personal property: Covers belongings if damaged or stolen.
- Liability protection: Provides financial protection in case a guest is injured on your property.
- Other structures: Coverage for free-standing structures on your property, e.g., sheds or fences.
- Additional living expenses: Covers costs if home becomes uninhabitable due to a covered loss.
Filing a Mobile Home Insurance Claim in Texas:
Filing a Mobile Home Insurance Claim in Texas:
- Insurance companies must acknowledge the claim within 15 days.
- Companies have 15 business days to accept or deny a claim, with potential for extensions in the event of major disasters.
- Possible 45-day decision timeframe if reasons are provided for delay.
- Failure to adhere to deadlines could result in the company being sued for the claim amount, interest, and legal fees.
Tips for Purchasing Mobile Home Insurance in Texas:
Tips for Purchasing Mobile Home Insurance in Texas:
- Mobile home insurance is often pricier than standard homeowners insurance.
- Best way to get affordable rates is to compare quotes from various companies.
- Online quotes might not be available; be prepared to call companies.
- Customizable policy options available to cater to individual needs.
Remember, while insurance might seem optional, it provides invaluable peace of mind against potential financial setbacks.
Choosing the Ideal Texas Homeowners Insurance Policy:
Choosing the Ideal Texas Homeowners Insurance Policy:
The apt insurance policy largely hinges on your home type, repair or rebuilding costs, and the worth of your belongings. It’s often a smart move to opt for the most robust protection within your budget. This is especially true if you haven’t set aside a significant emergency fund. Though a comprehensive policy with a lower deductible might require higher premiums, it ensures quick recovery after a substantial loss.
As your savings grow, you might consider increasing your deductible to decrease your premium. But here’s a pro tip: sometimes, a $1,000 deductible isn’t much pricier than a $5,000 one. In such instances, the minimal extra expense can prove invaluable in the event of a large claim.
The location of your mobile home, particularly the zip code in Texas, is a significant factor.
The location of your mobile home, particularly the zip code in Texas, is a significant factor.
You Need: The HO-7: Texas Mobile Home Form
You Need: The HO-7: Texas Mobile Home Form
- For Texas residents who own a mobile home, the HO-7 insurance form is crucial.
- This insurance covers both your dwelling and personal property.
- The HO-7 offers comparable coverage to the HO-3 policy.
- One thing to remember: if you plan on moving your mobile home, the HO-7 doesn’t always cover it while in transit. You may need to consider supplemental insurance in such cases.
What Does an HO-7 Policy Cover?
Type of Homes: Mobile or manufactured homes (trailers, single/double-wide mobile homes, RVs, modular homes, etc.).
Property (Dwelling & Other Structures)
Contents (Personal Property)
Dwelling & Other Structures
Personal Property
Valuable Items
Liability
Loss of Use
Medical Payments
What Does an HO-7 Policy NOT Cover?
Personal property damage that doesn't fit the named perils. Exclusions include:
- Floods
- Hurricanes
- Mold (Limited Coverage Might be Possible to Add)
- Earthquakes (Separate Policy Might be Available)
- Vandalism to Vacant Dwellings
- Wear and Tear
- Damage From Pets
- Intentional Acts
- Neglect
- Government Actions
Understand The HO-3: Texas Special Form
The HO-3 policy is the predominant homeowners insurance in Texas. It offers open-peril coverage for homes and related structures, covering all damages unless specifically excluded. Exclusions typically include:
- Earthquakes
- Floods
- Damage from insects & vermin
- Wear, neglect, or intentional damage
- Wind/hail damage to trees
- Vacancies, continuous water leaks
- Sewer backups, acts of war
- Certain mold cases
Additional Insurance Policy Options:
Even if you’ve chosen the HO-7 or another base form for your policy, you might still want to contemplate additional coverage for specific scenarios. Here are some prevalent options:
Texas DP-1 Insurance
Texas DP-3 Insurance
Personal Umbrella Policy
Scheduled Personal Property Coverage
Water Backup Coverage
Unmitigated Disasters
Choosing the Right Mobile Home Insurance for Georgetown, TX.
Ice Storms and Severe Cold Weather
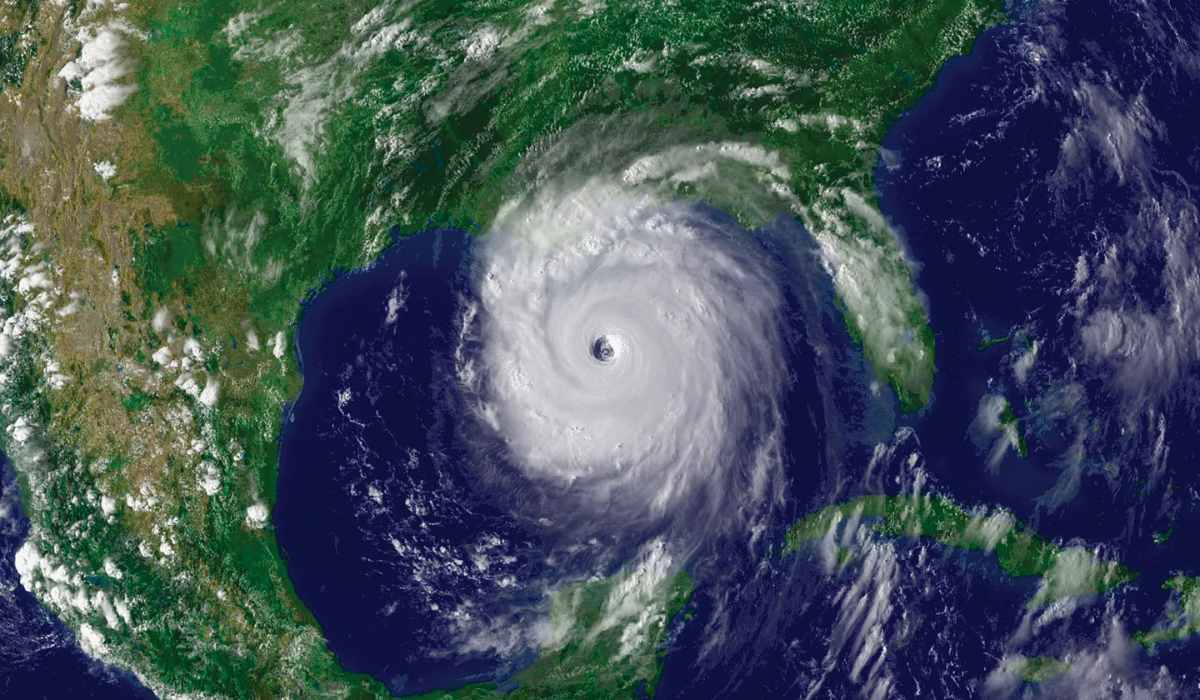
2023 Ice Storm Impact: In 2023, Central Texas, including Georgetown, experienced a severe ice storm, resulting in residents going without electricity for days. The storm damaged trees and power lines significantly. City officials reported almost 120,000 cubic yards of tree debris, surpassing the 30,000 cubic yards of debris from the 2021 winter storm.
Insurance Implications for Mobile Home Owners Extended periods without power, potential damage from falling trees, and the challenges of insulating mobile homes can increase insurance claims during such events.
Heat and Drought Conditions
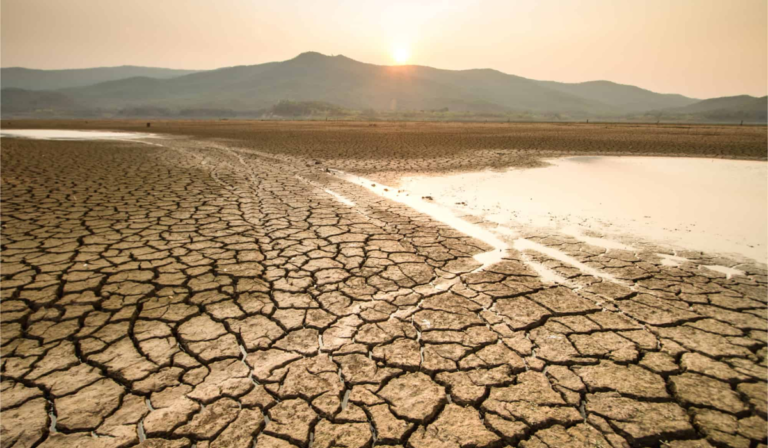
Heat Risks: Georgetown faces severe heat risks with "feels like" temperatures soaring. 98% of homes in Georgetown are at risk of falling under severe heat temperature ranges, with around 33,543 properties at risk.
Insurance Concerns for RV Owners: Prolonged exposure to excessive heat can damage RVs, with issues ranging from appliance malfunctions to interior damage.
Flood Risks & Wind Risks
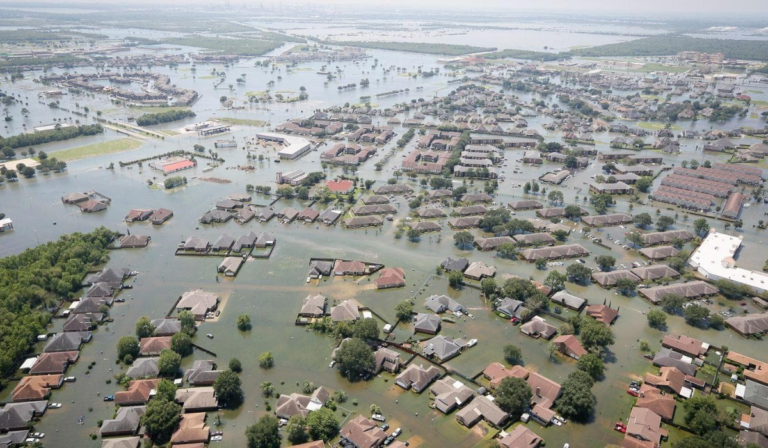
Overview: 1,674 properties in Georgetown face a significant chance of being severely impacted by flooding over the next 30 years. Flooding can disrupt utilities, transportation, emergency services, and economic stability. Georgetown experiences severe wind risks, predominantly from hurricanes. Over the last three decades, average maximum wind speeds have increased. 25% of homes face some wind risks.
Implications for Mobile Park Owners & RV owners: Flooding can cause extensive damage to the infrastructure of mobile parks, making flood insurance essential. High wind speeds can overturn or damage RVs, emphasizing the importance of comprehensive wind insurance.
We do insurance better. And here’s how.
- Save an average of $250 per year
- File a claim in 3 minutes
- Easily manage your policy online
- Skip the faxing, long paperwork, and unnecessary phone calls
- Get support from an American-based team
Are you in Georgetown, TX, looking for mobile home insurance
Choice of 6 insurance coverage in Georgetown, TX.
Cyber Security Coverage
What it is: Protection against risks related to digital threats, like hacking, data breaches, or ransomware. Why it's needed: As homeowners increasingly rely on smart devices and home networks, they become targets for cyber-attacks, making this coverage ever more essential.
Vandalism and Malicious Mischief Coverage
What it is: Protects against damages or losses resulting from deliberate acts of destruction or harm. Why it's needed: Provides peace of mind in areas where vandalism might be a concern, ensuring that damages are covered.
Appliance Leakage
What it is: Coverage for damages specifically caused by leaks from appliances. Why it's needed: Appliances can sometimes malfunction, leading to expensive water damages.
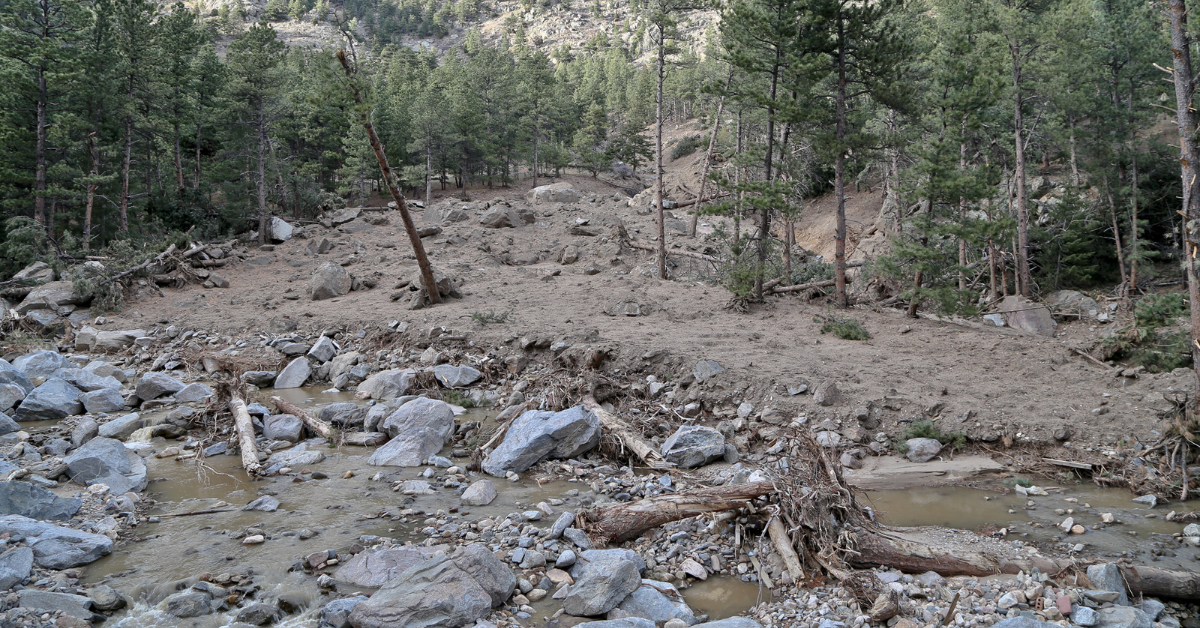
Mudflow Protection
What it is: Protection against damage caused by mudflow. Why it's needed: In areas prone to heavy rains or near mountains, mudflows can pose a significant risk.
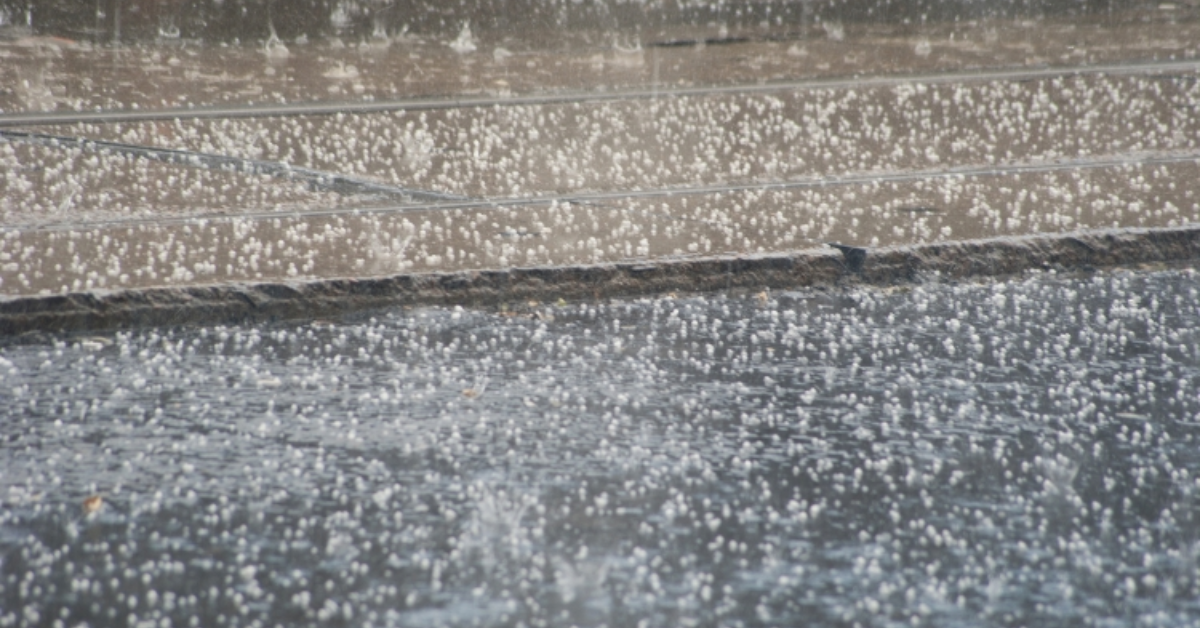
Windstorm and Hail Coverage
What it is: Protects against damages from windstorms and hail. Why it's needed: Especially vital in regions prone to strong winds or frequent hailstorms.
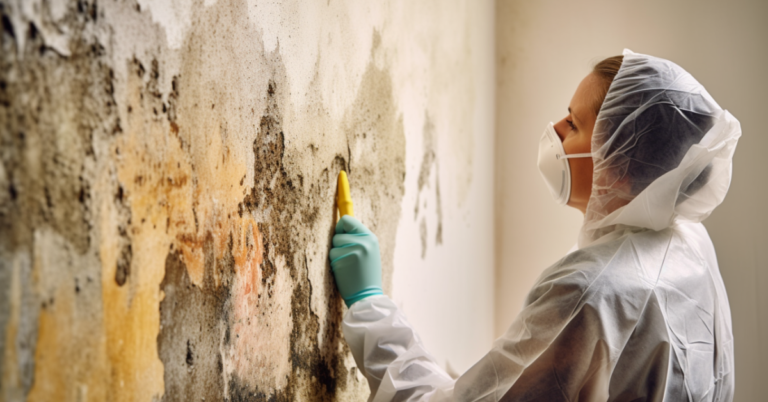
Mold Remediation Coverage
What it is: Covers costs related to mold removal and repair. Why it's needed: Mold can lead to health problems and structural damage. Mobile homes, especially in humid areas, may be vulnerable.
Mobile Home Facts : Texas
Treatment of Manufactured Home as Real Property:
- Once a “real property election” for a manufactured home is completed, the home is deemed as real property.
- This status remains unless the home is moved, the election changes, or the property’s use alters.
- Once a statement of ownership and location is given by the department, it’s final. Changes can only be made if all parties agree, or specific procedures are followed.
- If taking responsibility for a Statement of Ownership, ensure all housing department steps are followed, including necessary notifications.
According to the Texas Underwriting Manual TX: 12.24:
- 12.24.3: Any manufactured housing unit on the property isn’t included in the land described in this commitment or policy.
- 12.24.4: Upon a lender’s request and payment as specified in R-11(e), the T-31 and/or T-31.1 Endorsements can be issued; T-31.1 can be given to both the owner and the lender.
Learn about Texas Homeowner Assistance: Two Vital Programs!
Texas residents who are struggling with home-related expenses have two vital assistance programs available: the Texas Homeowner Assistance Program due to the COVID-19 pandemic and the Homeowner Assistance Program (HAP) following Hurricane Harvey.
Treatment of Manufactured Home as Real Property:
Purpose: Support homeowners impacted by Hurricane Harvey to repair, rebuild, and enhance their homes.
Services Offered: Financial support for affected homeowners.
Homeowner Assistance Program (HAP):
Purpose: Support homeowners impacted by Hurricane Harvey to repair, rebuild, and enhance their homes.
Services Offered: Home repairs and rehabilitation I Home reconstruction I Enhancements for better resilience against natural disasters I Elevating homes above flood levels along with reconstruction aid I Temporary relocation aid
Residents are encouraged to assess their eligibility and take advantage of these programs to secure and improve their homes.
Texas Coastal Property Insurance Pool Programs!
The Texas Coastal Insurance Pool (TCIP), formerly known as the Texas Windstorm Insurance Association (TWIA), is a vital insurance entity designed to protect homeowners in the Texas coastal regions. Established in the face of limited private insurance options, the TCIP provides wind and hail coverage to properties located in certain parts of Texas’s seacoast territory.
Key Features:
Rates:
Inland of the Intracoastal Canal $2.50 per $100 coverage 42 Effective October 1, 2008 Seaward of the Intracoastal Canal $5.00 per $100 coverage
Eligibility for TWIA:
A mobile home located in a designated catastrophe area that meets the following criteria is eligible to be insured under the T.W.I.A. Dwelling Policy with Form No. TWIA-411, Conversion to TWIA Manufactured Home Policy attached to the policy.
The mobile home complies with the definition of manufactured home under the rules and regulations of the Texas Department of Housing and Community Affairs (TDHCA). Criteria 2 The mobile home is occupied solely as a one or two family residence. Criteria 3Additions to Mobile Homes:
- A site-built addition attached to a mobile home will rate as part of the mobile home.
- A building certification from the Texas Department of Insurance is required for the site-built addition.
- Separate structures (not physically attached to the mobile home) are not eligible for insurance under the T.W.I.A. Dwelling Policy with Form No. TWIA411, Conversion to TWIA Manufactured Home Policy attached to the policy. Refer to eligibility requirements for insurance under the Association’s Dwelling Policy.
Deductibles:
- The following deductibles are mandatory under the T.W.I.A. Dwelling Policy with Form No. TWIA-411, Conversion to TWIA Manufactured Home Policy attached to the policy. a. Homes located inland of the Intracoastal Canal: 1% of limit of liability with a $250 minimum (TWIA Form No. 570) b. Homes located seaward of the Intracoastal Canal: 2% of the limit of liability with a $250 minimum (TWIA Form No. 575)
- Deductibles apply separately to the home and household goods items on the policy.
Limit of Liability:
The maximum limit of liability for a mobile home, including any site-built additions attached to the home, and household goods is $84,000.
Policy Forms & Endorsements:
The following policy form is to be used: T.W.I.A. Dwelling Policy with Form No. TWIA-411, Conversion to TWIA Manufactured Home Policy attached to the policy
Know Your Rights!
About – Central RV Park Parkside – Longterm RV Park Georgetown TX 55+
Additional Policy Riders for Mobile Home Insurance in Texas:
Adding policy options to a basic insurance plan is a common practice in the mobile home insurance industry. While the events covered in mobile home policies are similar across all states, additional coverage options, known as add-ons, endorsements, and riders, may vary depending on your location and insurance provider. Each of these options comes at an additional cost that can be customized according to your needs.
Provides protection against flood-related damages, excluding waterline or sewer backups. Average annual cost: $700. Earthquake InsuranceAdding any rider will increase your premiums, influenced by location, risk profile, chosen coverage, and deductible. Riders can be added during initial policy purchase, at renewal, or anytime during the policy period. Some carriers might not offer all endorsements, so shopping around might be necessary.