
Insurance guides
Protect Your Manufactured Home in Aiken, SC
Disclaimer: Data Accuracy and Sources
The data in the Covertree Resources section is from publicly available sources last updated in December 2022. We provide source links for verification. However, we can’t guarantee accuracy. Rely on this data at your own discretion. For specific advice, consult professionals.
Welcome to Aiken, South Carolina – a city where the grace of Southern living is matched only by its rich equestrian heritage and the charm of its historic streets. Nestled in the heart of South Carolina’s Thoroughbred Country, Aiken is a community that celebrates its unique place in equestrian history, its beautiful antebellum homes, and a lifestyle that embodies the elegance and leisure of the Old South.
As you wander through the tree-lined streets of Aiken, you’ll immediately sense the city’s deep connection to the equestrian world. Renowned for its thoroughbred racing, polo matches, and horse shows, Aiken is a haven for horse enthusiasts. The Aiken Thoroughbred Racing Hall of Fame and Museum, located within the picturesque Hopelands Gardens, pays tribute to the city’s storied equestrian past and its champions.
The charm of Aiken extends beyond its equestrian ties. The city’s downtown area captivates with its blend of historic architecture, unique boutiques, and delightful cafes. Strolling through Aiken’s downtown, you’ll feel the warmth of a welcoming community that prides itself on its hospitality and vibrant cultural scene.
Aiken’s commitment to preserving its historical and natural beauty is evident in its well-preserved antebellum homes and the stunning gardens and parks that dot the city. The Hitchcock Woods, one of the largest urban forests in the United States, offers miles of walking and riding trails amidst a backdrop of towering pines and serene woodlands.
The culinary experience in Aiken is a reflection of its Southern roots, with a twist of contemporary flair. From classic Southern cuisine to innovative dishes that showcase local ingredients, the city’s dining scene is rich with flavors that cater to a variety of palates. The city’s local food festivals and culinary events are celebrations of Aiken’s gastronomic diversity and the community’s love for good food.
Aiken is also a city of arts and culture. The Aiken Center for the Arts offers a space for local artists to showcase their work, while various cultural events throughout the year celebrate the city’s artistic and creative talents. These events bring together residents and visitors alike in a shared appreciation for the arts.
Education and community involvement are central to life in Aiken. The city’s schools and institutions, including the University of South Carolina Aiken, foster a culture of learning and engagement, ensuring that Aiken continues to thrive as a knowledgeable and tight-knit community.
In Aiken, South Carolina, every oak-lined avenue, historic home, and gentle horse’s whinny tells a story of a city that treasures its past, enjoys its present, and embraces its future. Welcome to Aiken, where the elegance of equestrian tradition, the charm of Southern living, and the beauty of historical preservation come together to create a community that is as captivating as it is welcoming.
Understanding Mobile Home Insurance in South Carolina
South Carolina law, under Title 38 - Insurance, specifically addresses mobile home and manufactured home insurance in several key sections. These laws dictate that mobile home insurance policies cannot exceed three years in duration and must offer full refunds of unearned premiums if the policy is canceled.
The law also:
- Restricts the amount of insurance that can be written, ensuring it does not exceed the property’s value.
- Mandates that information about these insurance requirements must be clearly stated in mobile home purchase contracts.
- Specifies that insurers cannot force policyholders to buy insurance from a particular company or agent, preserving the buyer’s freedom to choose their insurer.
- Aims to protect mobile home owners and ensure fair and transparent insurance practices.
In addition to the regulations on policy duration and refunds, South Carolina law also includes:
- Provisions ensuring fair and reasonable insurance practices for mobile homes.
- For instance, policies must clearly state the maximum amounts for which they can be written, aligning with the property’s actual value, to prevent over-insurance.
- In cases of total loss, the insured is entitled to recover the full insurance amount, while in partial losses, they are only entitled to the actual loss amount, not exceeding the policy’s limit.
- Regulations regarding the distribution of unearned premiums in the event of a policy cancellation, ensuring that any unearned portion is refunded fully or applied appropriately.
- These measures are in place to protect mobile home owners from unfair insurance practices and financial losses, providing a level of security and clarity in their insurance coverage.
Do I Need Mobile Home Insurance in South Carolina?
Opting for mobile home insurance, although not legally mandatory, is a prudent choice, especially if you're considering a mortgage on your mobile home. Given the average value of a mobile home is at around $83,000, securing insurance is a strategic move to safeguard your home and personal property. Despite the potential expense, the lack of insurance exposes you to significant financial risks in the event of damage or loss.
Cost of Mobile Home Insurance in SC
Average Cost:
Factors Influencing Cost:
- Mobile Home Value: More expensive homes may have higher insurance costs.
- Location: Areas prone to natural disasters or high crime rates might see increased rates.
- Age of Mobile Home: Older homes might incur higher insurance costs due to increased risk of damage.
- Coverage Limits and Deductibles: Choosing higher coverage limits or lower deductibles can increase premiums, while opting for basic coverage with higher deductibles may reduce the cost.
Getting Quotes:
Coverage Details
Physical Damage:
Mobile Home Damage:
Personal Property:
Personal Liability:
Other Structures:
Living Expenses:
Additional Considerations
In summary, while mobile home insurance is not legally mandated, it offers significant financial protection against a range of potential risks and damages. The cost can vary based on several factors, and it's important to thoroughly understand what is covered under your policy, especially for specific risks like natural disasters.
Customization:
Natural Disaster Coverage:
Comparative Shopping:
Understanding Coverage Exclusions in Mobile Home Insurance
Mobile home insurance, much like standard homeowners policies, comes with certain exclusions. It's important to be aware of these to understand the extent of your coverage. Common exclusions typically include:
Sewer Backups:
Earthquakes:
Floods:
In-Transit Incidents:
Zoning Laws
Routine Maintenance:
Pest Control:
Deterioration and Rust:
Home-Based Business:
Mold:
Exploring Additional Insurance Options
For the above exclusions, you may have the option to purchase additional, separate insurance policies. It’s advisable to consult with an insurance agent to discuss available options and ensure comprehensive coverage for your mobile home. This proactive approach can help fill any gaps in your standard policy and provide peace of mind.
Exploring Additional Insurance Options
Understanding Hazard Insurance on Mobile Homes in South Carolina
Hazard insurance for mobile homes is a specific type of insurance policy designed to protect homeowners from various risks and damages specifically related to mobile homes. This insurance typically covers losses from events like fires, storms, theft, and other hazards that can cause physical damage to a mobile home. In South Carolina, certain regulations and provisions under the state law govern the issuance, duration, and terms of these policies, ensuring fair practices and protection for mobile home owners. Here's a detailed look at the key aspects of Hazard Insurance on Mobile Homes as outlined in Article 3 of the South Carolina Code of Laws:
Understanding Hazard Insurance on Mobile Homes in South Carolina
Policy Duration Limit (SECTION 38-75-210):
- Hazard insurance policies for mobile homes in South Carolina are limited to a maximum term of three years.
- If a policy is canceled, premiums for the unused term are considered unearned and must be fully refunded, whether the cancellation is initiated by the insurer or the insured.
- Refund policies vary depending on the timing of the cancellation relative to the policy term.
Insurance Amount Restrictions (SECTION 38-75-220):
- Insurers cannot issue a policy for a value exceeding the mobile home’s stated value or actual property value.
- The insurance amount must be agreed upon between the insurer and the insured at or before issuing the policy.
- In the event of a total loss due to an insured hazard, the insured is entitled to the full insurance amount. For partial losses, the payout is the actual loss amount, up to the insured value.
- Policies on the same property are considered contributive, and insurers share liability proportionately if the total insurance exceeds the home’s insurable value.
Contract Requirements for Mobile Home Purchase (SECTION 38-75-230):
- Contracts for purchasing a mobile home must include provisions of SECTION 38-75-210.
- The contract must inform buyers that it is illegal in South Carolina for a mobile home seller or a lender to require the buyer to purchase hazard insurance from a specific insurer or agent. This section also provides information on where to report violations of this law.
These regulations ensure that mobile home owners in South Carolina are adequately protected and informed about their rights and obligations regarding hazard insurance.
Overview of Wind and Hail Insurance in South Carolina
Wind and Hail Insurance is a specific type of property insurance in South Carolina, focusing on covering losses due to windstorms and hail, particularly in the state's coastal areas. This insurance is crucial for homeowners and property owners in regions prone to such natural hazards. The following are key sections from the South Carolina Code of Laws that detail the regulations and structures governing Wind and Hail Insurance:
Overview of Wind and Hail Insurance in South Carolina
Definitions (SECTION 38-75-310):
- Essential Property Insurance: Coverage against direct loss to property defined in the wind and hail insurance policy. It may include business income loss, additional living expense, or fair rental value loss.
- Association: Refers to the South Carolina Wind and Hail Underwriting Association.
- Plan of Operation: The operational plan of the association, as approved by the department.
- Insurable Property: Immovable or tangible personal property in specific coastal areas, subject to certain conditions and standards.
- Coastal Area: Defined regions in South Carolina’s counties like Beaufort, Colleton, Georgetown, Horry, and Charleston, among others.
Declaration of Purpose (SECTION 38-75-320):
- The article aims to ensure a sufficient market for wind and hail insurance in South Carolina’s coastal areas.
South Carolina Wind and Hail Underwriting Association (SECTION 38-75-330):
- Creation of the association, comprising private insurers authorized to write property insurance in the state, to provide wind and hail insurance in coastal areas.
Plan of Operation (SECTION 38-75-340):
- Details the administrative structure of the association, including board composition, management, underwriting standards, rates, and procedures for processing insurance applications.
Application for Coverage (SECTION 38-75-350):
- Procedure for applying for coverage, conditions for issuing policies, and the appeal process for denied applications.
Powers of the Association (SECTION 38-75-360):
The association’s authority and responsibilities, including issuing policies, reinsurance activities, property management, contracting, and financial transactions.
These sections collectively establish the framework for providing wind and hail insurance in South Carolina's coastal areas, ensuring adequate protection for properties against these specific natural hazards.
Learn About The South Carolina Wind and Hail Underwriting Association (SCWHUA)
also known as the Wind Pool, plays a crucial role in providing wind and hail insurance coverage in the coastal areas of South Carolina, particularly for those who cannot obtain such coverage through the standard insurance market. Here's an overview of key aspects of the SCWHUA:
Overview
- Purpose: SCWHUA was established to ensure the availability of wind and hail insurance for home and business owners in coastal areas, particularly those close to the coastline where standard insurance is often unavailable.
- Territory Covered: The coverage is specifically for the coastal areas designated by the South Carolina Legislature as “Beach.”
Operation and Eligibility
- Board of Directors: The Association is governed by a Board comprising 11 insurance company representatives, 2 coastal insurance agents, and 4 consumer representatives.
- Eligibility: Coverage is available to almost anyone in the designated coastal area of South Carolina. The Association is considered a market of last resort, and it is recommended to seek insurance in the standard market first.
Claims Handling
- Process: In the event of a loss, insured parties should promptly contact their insurance producer and provide a list of damaged or destroyed items. Protection against both wind and water damage, including storm surges and high tides, is emphasized.
- Flood Insurance: Policyholders are advised to discuss flood insurance with their agents, as it’s a separate consideration.
Comparison Shopping
Agents and Coverage
- Agents: All business must be handled by an independent agent chosen by the consumer. Producers, who are licensed by the South Carolina Department of Insurance, can submit applications but have no authority to make decisions on behalf of the Association.
- Coverages: The Association offers a limited peril policy for wind and hail damage. Coverage limits for personal and commercial risks are up to $1.3 million and $2.5 million, respectively. Policies are written annually.
Property Standards and Compliance
Policy Initiation and Continuation
- New Policies: Coverage begins 16 days after the online submission of a completed application.
- Renewals: For continued coverage, a new application and premium payment are required annually. Rewrite policies must be submitted online within 7 days of policy expiration.
Cancellation, Non Renewal, and Renewal of Property Insurance and Casualty Insurance (SECTIONS 38-75-710 to 38-75-790)
These sections collectively provide a regulatory framework ensuring fair practices in the insurance industry, especially concerning policy renewals and cancellations, while also promoting risk mitigation and public awareness about insurance options and rights.
Scope and Definitions:
Restrictions and Notice Requirements:
Non Renewal Procedures:
Renewal Requirements:
Notification Requirements:
Unlawful Practices:
Coverage for Health Care Providers:
Liability Exemptions:
Protection Against Non Renewal for Acts of God:
RV Insurance Facts in SC:
South Carolina: A Haven for RV Travelers
With destinations ranging from the picturesque Myrtle Beach to the wilderness of Congaree National Park, South Carolina is a prime spot for RV travel. An RV not only offers a cost-effective alternative to traditional travel but also enriches the experience with its flexibility. However, prior to journeying through the Palmetto State, it's vital to grasp the essentials of RV insurance in this region.
Legal Requirements for RV Insurance in South Carolina
1) Drivable RVs must have bodily injury liability, property damage liability, and uninsured motorist coverage.
2) If your RV is financed, lenders may require comprehensive and collision coverage.
Key Components of RV Insurance in South Carolina
RV insurance in the state encompasses a variety of protections, extending to your vehicle, other properties, and individuals involved in accidents. Understanding these components ensures comprehensive coverage:
Mandatory Liability Coverage
- Bodily Injury Liability: Essential for all drivable RVs, this coverage handles medical expenses of others in accidents where you’re liable. South Carolina mandates a minimum coverage of $25,000 per person and $50,000 per accident.
- Property Damage Liability: This coverage, also compulsory, caters to damages you cause to others’ property during accidents, with a statutory minimum of $25,000 per incident.
Additional Insurance Options
- Uninsured/Underinsured Motorist Coverage: Protects you against damages caused by uninsured drivers, with mandated limits akin to bodily injury liability.
- Collision Coverage: Irrespective of fault, this option covers damages to your RV in accidents.
- Comprehensive Coverage: This broad coverage includes non-collision-related damages like theft, natural disasters, and vandalism.
- Medical Payments Coverage: Addresses medical expenses for injuries within your RV, beneficial regardless of fault.
- Personal Effects Replacement: Aids in replacing personal belongings damaged, destroyed, or stolen from your RV.
- Total Loss Replacement: Particularly useful for newer RVs, offering replacement or reimbursement post-totaling.
- Roadside Assistance and Towing & Labor: Provides aid during mechanical breakdowns, especially vital for drivable RVs.
- Vacation Liability Coverage: Offers protection against liabilities when your RV is parked at campsites.
Choosing the Right Mobile Home Insurance for Aiken, SC
Weather & Environmental Risks:
Being prepared and aware of the weather and environmental risks in Aiken, SC is crucial for mobile homeowners, RV owners, and others residing or staying in the area. Stay informed, have an emergency plan in place, and take necessary precautions to ensure your safety during weather events.
Severe Thunderstorm and Tornado Risk
- Aiken, SC has a moderate risk of severe thunderstorms and tornadoes.
- Severe thunderstorms can bring strong winds, hail, and the potential for tornadoes, which can cause significant damage.
- On average, the area experiences about 44 thunderstorm days per year.
- Tips for mobile homeowners and RV owners in areas prone to severe thunderstorms:
- Have a plan in place for seeking shelter during severe weather events.
- Stay informed by monitoring weather forecasts and having a reliable source for receiving weather alerts, such as a weather radio or mobile app.
- Secure outdoor items and bring in patio furniture, grills, and other objects that could become windblown projectiles.
- Park your mobile home or RV away from trees and power lines to reduce the risk of falling limbs or downed electrical lines.
Flooding and Heavy Rainfall Risk
- Aiken, SC is susceptible to periods of heavy rainfall, which can lead to localized flooding.
- Flooding can occur in low-lying areas, near rivers, and due to poor drainage systems.
- Tips for mobile homeowners and RV owners in flood-prone areas:
- Be aware of flood zones in the area and familiarize yourself with evacuation routes and emergency shelters.
- Park your mobile home or RV on higher ground to minimize the risk of water damage. Avoid low-lying areas or near rivers and streams.
- Ensure your vehicle is equipped with good tires and avoid driving through flooded roadways.
- Keep important documents, such as insurance papers and identification, in a waterproof container.
Extreme Heat and Drought Risk
- Aiken, SC experiences hot and humid summers, with occasional heat waves and drought conditions.
- High temperatures and prolonged heat waves can pose health risks, while drought conditions can impact water availability and agricultural practices.
Tips for mobile homeowners and RV owners in areas with extreme heat and drought
- Stay hydrated by drinking plenty of water and avoid prolonged outdoor activities during the hottest times of the day.
- Use shade and fans to keep cool in your mobile home or RV, and utilize air conditioning if available.
- Limit water usage and be aware of any drought restrictions or guidelines in place.
- Protect your skin from the sun’s rays by wearing sunscreen, sunglasses, and lightweight, loose-fitting clothing.
Crime Rates:
Crime Rate in Aiken
- Aiken has a relatively lower crime rate compared to the national average, with lower rates of both violent and property crimes.
- The chance of becoming a victim of either violent or property crime in Aiken is lower compared to many other communities.
- Aiken is considered a safer community compared to some other areas in the region.
Violent Crimes in Aiken
- Violent crimes in Aiken include offenses such as assault, robbery, and murder.
- The rate of violent crime in Aiken is lower compared to many other communities.
- Law enforcement agencies are actively focused on maintaining a safe environment in Aiken.
Property Crimes in Aiken
- Property crimes in Aiken include burglary, theft, motor vehicle theft, and arson.
- The rate of property crime in Aiken is lower compared to many other communities.
- Residents and visitors should still take necessary precautions to protect their property and belongings.
Tips for Mobile Homeowners, RV Owners, etc.
- Research the safety and security measures of mobile home parks and RV parks in Aiken before selecting a location.
- Choose parks that prioritize security, such as those with gated entrances, surveillance cameras, and active community watch programs.
- Implement security measures for your mobile home or RV, such as installing alarms, using strong locks on doors and windows, and utilizing visible deterrents like lighting or cameras.
- Establish communication with neighbors and consider joining or starting a neighborhood watch group to enhance community safety.
- Stay informed about any local crime trends, and report any suspicious activity promptly to law enforcement.
While Aiken generally has a lower crime rate, it's still important to remain cautious and take necessary precautions. Stay informed about local safety resources and initiatives, and maintain open communication with law enforcement agencies and community organizations for guidance on crime prevention and specific safety tips for mobile homeowners and RV owners.
We do insurance better. And here’s how.
- Save an average of $250 per year
- File a claim in 3 minutes
- Easily manage your policy online
- Skip the faxing, long paperwork, and unnecessary phone calls
- Get support from an American-based team
Are you in Aiken, SC, looking for mobile home insurance
Additional Tips:
Understand Lease Agreements
If renting a lot in a manufactured home community, thoroughly understand your lease agreement, focusing on rules, regulations, and eviction terms.
Mobile Home Skirting
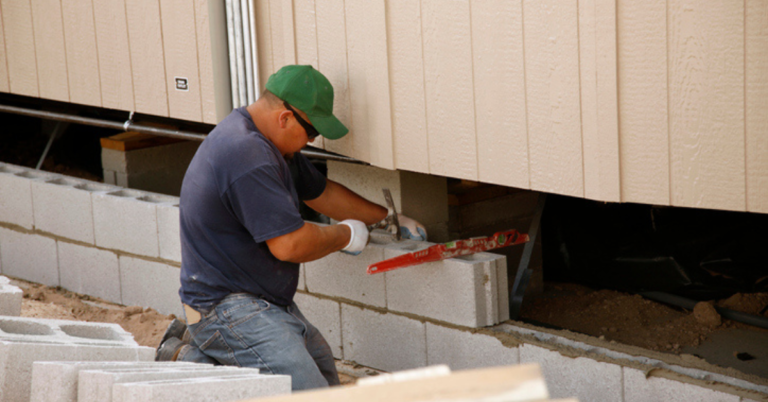
Maintain the skirting of your mobile home. This not only improves aesthetics but also protects the underside from animals and weather damage.
Accessibility Modifications
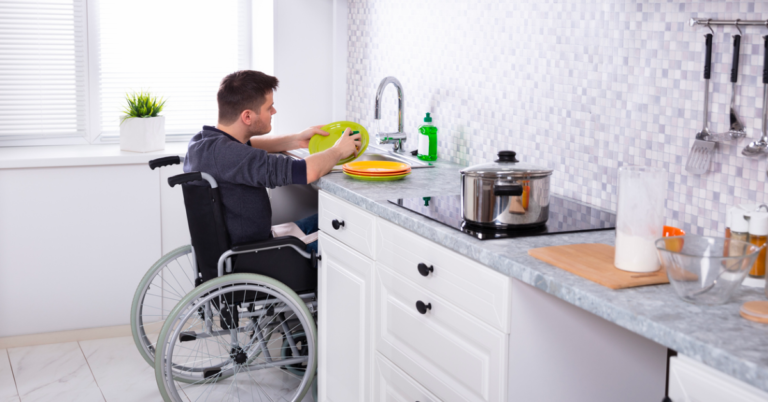
Consider modifications for accessibility if you or a family member has mobility challenges.
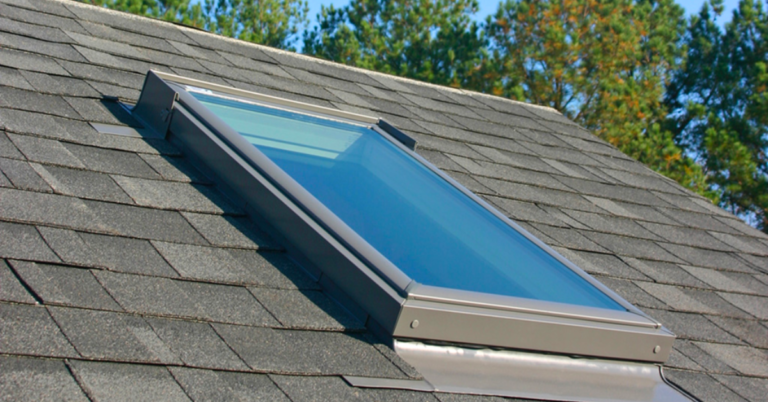
Roof Maintenance
Regularly inspect and maintain your roof to prevent leaks and water damage, especially before the rainy and hurricane seasons.
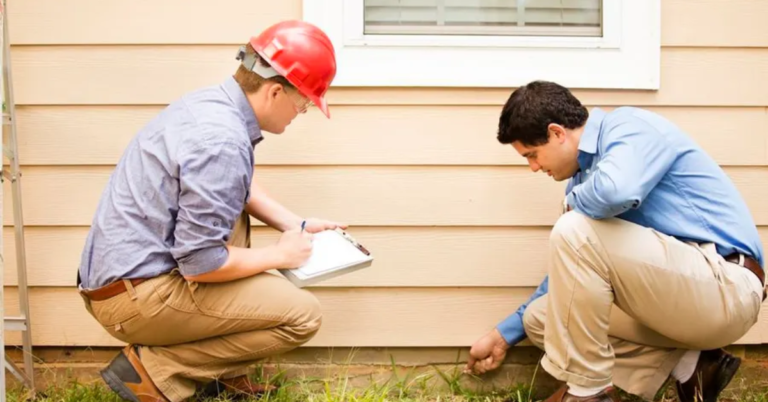
Foundation Checks
Regularly check the foundation and anchoring of your mobile or manufactured home, as shifting can occur over time.
Participate in Community Boards or Associations
Get involved in your community's decision-making processes, if available, to have a say in community developments and improvements.
South Carolina Home Facts
In South Carolina, with a population exceeding 4.7 million, the typical sales price for a standard home is around $225,000. In contrast, modular homes in the state are more budget-friendly, averaging between $50 to $70 per square foot. This puts the average cost of a modular home at about $108,000, presenting a cost-effective option for those looking to buy a home in South Carolina. However, it’s important to note that in urban areas like Columbia and Charleston, prices can be higher due to more expensive land and site development costs.
In SC, around 20% of South Carolina families, equating to over 355,000 households, reside in manufactured homes. This choice is popular due to the state’s vast agricultural lands and appealing coastline, ideal for both farming and family living. Some interesting aspects of mobile home living in South Carolina include:
- The average cost of a previously owned home is approximately $69,166.
- The typical pre-owned home in the state dates back to around 2006.
- These homes usually offer about 1540 square feet of living space.
- An average manufactured home community in South Carolina consists of around 126 homes.
- Most of these communities were established in or around 1983.
- There are 27 age-restricted communities, alongside 339 communities suitable for all ages.
Mobile Homes in SC – Did You Know?
Here are 10 facts about mobile/manufactured homes and RVs in South Carolina:
- High Prevalence: South Carolina has one of the highest rates of mobile homes per capita in the United States, with these homes comprising over 20% of the state’s housing units.
- Affordability: Mobile homes offer an affordable housing alternative in South Carolina, with prices significantly lower than conventional homes.
- Distribution: Mobile homes are found in nearly every ZIP code across South Carolina, reflecting their widespread popularity.
- Construction and Classification: Mobile homes are typically factory-built and transported to their location, whereas modular homes, also prevalent in the state, are assembled on-site and often categorized similarly to traditional homes by insurance companies.
- Susceptibility to Weather: Due to their construction, mobile homes in South Carolina are particularly vulnerable to damage from the state’s frequent strong winds, heavy rains, and hurricanes.
- Installation Regulations: South Carolina has specific regulations (S.C. Code Regs. § 79-42) governing the installation of manufactured homes, focusing on safety and durability.
- RV Popularity: Recreational Vehicles (RVs) are popular in South Carolina, especially in coastal areas and near tourist destinations like Myrtle Beach, due to the state’s scenic beauty and mild climate.
- RV Parks and Campgrounds: The state boasts numerous RV parks and campgrounds, catering to both short-term vacationers and long-term residents.
- Insurance Considerations: Insurance for mobile homes and RVs in South Carolina is crucial due to the high risk of natural disasters. Standard policies typically cover a range of perils but may exclude specific events like floods and earthquakes.
- Economic Impact: The mobile home and RV industries contribute significantly to South Carolina’s economy, not just in sales and manufacturing but also through tourism, parks, and associated services.
These facts highlight the significance of mobile/manufactured homes and RVs in South Carolina’s housing landscape and economy, as well as the unique challenges and opportunities they present.
Manufactured Housing Institute of South Carolina
The Manufactured Housing Institute of South Carolina (MHISC)- is a non-profit business association representing the manufactured and modular housing industries in South Carolina. Founded in 1967, the member-run organization aims to maximize opportunities for South Carolinians to enjoy the benefits of factory-built homes.
MHISC’s mission is to create a regulatory climate at the state and local level that allows the industry to thrive. They work towards favorable laws benefiting member companies and create marketing opportunities within the industry and with future customers.
The association operates two divisions: the Manufactured Housing Institute of SC and the SC Modular Housing Institute. MHISC is an active member of the National Manufactured Housing Institute in Washington and the National Modular Housing Council. They have six local chapters: Charleston, Grand Strand, Midlands, Low Country, Pee Dee, and Upstate Chapters.
The staff at MHISC has years of experience in association management, marketing, media relations, membership services, political development, local government planning, and business management. They are dedicated to providing excellent service to members and educating the public and state and local policy-makers about the benefits of manufactured homes.
For more information on membership, resources, and other inquiries, visit the MHISC website.
Disclaimer: The information provided here regarding mobile and manufactured homes in South Carolina, including pricing, statistics, and community details, is intended for general informational purposes only. It is based on data and estimates that may vary and is subject to change over time. This information should not be used as a sole basis for making financial, investment, or any other decisions. Actual prices and conditions can differ based on specific locations, market changes, and other factors. It is advisable to conduct thorough research and consult with real estate professionals or other relevant experts for current and detailed insights before making any property-related decisions.
Know Your Rights:
- South Carolina Code of Laws
- South Carolina Manufactured Housing Laws and Regulations
- Code of Laws of South Carolina 1976 | Article 3 – HAZARD INSURANCE ON MOBILE HOMES | Casetext
- The Difference Between Mobile Homes And Manufactured Homes In South Carolina
- Do I Need Insurance For My Mobile Home In South Carolina?
Finding the Best Mobile Home Insurance in Aiken, SC
It’s essential to compare quotes from various insurance providers and work with local agencies that understand Aiken’s specific risks.
These are some things you should look out for in an insurance plan for Aiken:
When insuring your mobile or manufactured home or RV in Aiken, SC, it’s important to consider the specific location hazards, property crime risks, and weather patterns in the area. Here are some unique factors to consider and relevant insurance options:
Aiken is located inland, so it’s not as vulnerable to hurricane or tropical storm damage. However, there is still a risk of tornadoes and thunderstorms. Ensure your policy includes coverage for Windstorm Damage to protect your mobile or manufactured home or RV against damages caused by wind.
Aiken generally has a higher property crime rate compared to other areas. Protect your mobile or manufactured home or RV against theft or vandalism by adding Comprehensive Coverage to your policy.
- As mentioned earlier, Aiken is at risk of tornadoes and thunderstorms. Ensure your policy provides specific coverage for damages to your mobile or manufactured home or RV’s roof and other structures in case of a wind storm.
- In addition, Aiken is at risk of flooding due to its location near rivers and streams. Protect your mobile or manufactured home or RV from flood damage by adding Flood Insurance to your policy.
- Earthquake Coverage: Although earthquakes are not as common in Aiken, it can still be beneficial to have Earthquake Coverage as an endorsement to protect your mobile or manufactured home or RV in the event of seismic activity.
- Personal Property Coverage: Mobile or manufactured home and RV owners in Aiken should consider adding coverage for personal property, including items such as furniture, electronics, and appliances.
- Additional Living Expense Coverage: This coverage helps cover the costs of temporary housing or additional living expenses if you cannot stay in your mobile or manufactured home or RV due to a covered loss.
It is recommended that you consult with a local insurance agent who specializes in mobile and manufactured home insurance or RV insurance in Aiken, SC. They will have a better understanding of the specific risks and coverage needs in the area, ensuring you have adequate protection for your mobile or manufactured home or RV.
References: