
Insurance guides
Protect Your Manufactured Home in Pearland, TX
Disclaimer: Data Accuracy and Sources
The data in the Covertree Resources section is from publicly available sources last updated in December 2022. We provide source links for verification. However, we can’t guarantee accuracy. Rely on this data at your own discretion. For specific advice, consult professionals.
Welcome to Pearland, Texas – a shining beacon of natural beauty, cultural diversity, and vibrant growth!
Enter the embrace of Pearland, a city where verdant nature harmonizes with the pulse of urban development. Nestled in the Houston metropolitan area, this city invites you on a journey of discovery, where scenic trails and parks coexist with bustling shopping centers and diverse culinary landscapes.
In Pearland, walk amidst the whispers of trees and the harmonious song of birds in the John Hargrove Environmental Complex, a living testament to the city’s commitment to preserving nature’s beauty. The city is adorned with various other parks and green spaces, offering residents and visitors a breath of fresh air and a peaceful retreat from the hustle and bustle.
Yet, Pearland is not just a haven for nature enthusiasts. It stands as a symbol of vibrant growth and cultural diversity. From a small agricultural settlement in the late 19th century, Pearland has blossomed into one of the fastest-growing cities in Texas. Here, the spirit of innovation intertwines with a rich cultural tapestry that adds to the city’s allure.
The city’s historical roots are not forgotten amidst this modern expansion. The Sri Meenakshi Temple, an architectural marvel, stands as a beacon of the city’s diverse cultural heritage and offers a unique insight into Hindu traditions and spirituality. It’s one of the few traditional Hindu temples in the United States and is a significant attraction for both the curious and the devout.
Pearland’s culinary scene is as diverse as its population. Indulge in an array of global flavors, from savory Tex-Mex to exquisite Asian cuisines. Enjoy a leisurely meal at one of Pearland’s many restaurants, where Southern hospitality melds with international flair, offering a dining experience that tantalizes your taste buds while warming your heart.
The Pearland Town Center and other shopping destinations reflect the city’s contemporary vibe, where elegant boutiques and prominent brands cater to both the fashion-forward and the practical shopper. Beyond commerce, these spaces serve as gathering spots, where friends and families unite over shopping, dining, and entertainment.
Education holds a paramount place in the Pearland community. The city’s award-winning schools emphasize holistic learning and individual growth, preparing the youth to navigate the world with knowledge, confidence, and compassion. In Pearland, community events and festivals further enliven the city’s spirit. Annual celebrations, like the Winterfest, bring the community together to revel in the joys of the season, highlighting the unity and communal bonds that underpin the city’s progressive ethos.
Discover Pearland, a city where nature’s tranquility, cultural richness, and modern vibrancy converge, crafting a unique and welcoming mosaic for all who call it home or come to explore its many facets. Whether you’re traversing its scenic paths, delighting in its diverse culinary offerings, exploring its cultural landmarks, or enjoying the warmth and hospitality of its residents, Pearland promises a memorable and enriching experience.
Understanding Mobile Home Insurance In Texas.
Do I Need Mobile Home Insurance in Texas?
Do I Need Mobile Home Insurance in Texas?
- Optional, but often required by lenders and mobile home communities.
- Lenders can’t mandate coverage that surpasses home and content replacement value.
- Strongly recommended for financial protection against damages.
Texas Mobile Home Insurance Costs Explained
Texas Mobile Home Insurance Costs Explained
Mobile home insurance is essential for safeguarding your most valuable asset. Prices in Texas typically range from $250 to $1,300 annually, influenced by various factors. Deciding between actual cash value and replacement cost coverage will also impact both premiums and compensation amounts in case of a claim.
Insurance rates are influenced by:
Insurance rates are influenced by:
- Geographic area (land value, crime rate, and environmental threats).
- Home’s value, size, and location.
- Home’s age.
- Chosen liability coverage.
- Desired personal property coverage amount.
- Selected deductible.
- Actual Cash Value: Compensates the current value of the home, accounting for depreciation. *
- Replacement Cost: Covers the cost of a new, similar home regardless of the original home’s age or previous value. **
* e.g. A five-year-old home bought for $50,000 but now worth $35,000 will be compensated at $35,000.
** Typically has higher premiums but offers more compensation during a claim.
Unique Considerations for Texas Mobile Home Insurance!
Unique Considerations for Texas Mobile Home Insurance!
- Wind and hail coverage may be excluded for homes near the coast.
- Purchase flood insurance via the National Flood Insurance Program if difficult to find in the private market.
- For wind and hail coverage, consider Texas Windstorm Insurance Association (TWIA).
Mobile Home Insurance Coverage in Texas:
Mobile Home Insurance Coverage in Texas:
- Dwelling coverage: Protection for permanent structures attached to the home.
- Personal property: Covers belongings if damaged or stolen.
- Liability protection: Provides financial protection in case a guest is injured on your property.
- Other structures: Coverage for free-standing structures on your property, e.g., sheds or fences.
- Additional living expenses: Covers costs if home becomes uninhabitable due to a covered loss.
Filing a Mobile Home Insurance Claim in Texas:
Filing a Mobile Home Insurance Claim in Texas:
- Insurance companies must acknowledge the claim within 15 days.
- Companies have 15 business days to accept or deny a claim, with potential for extensions in the event of major disasters.
- Possible 45-day decision timeframe if reasons are provided for delay.
- Failure to adhere to deadlines could result in the company being sued for the claim amount, interest, and legal fees.
Tips for Purchasing Mobile Home Insurance in Texas:
Tips for Purchasing Mobile Home Insurance in Texas:
- Mobile home insurance is often pricier than standard homeowners insurance.
- Best way to get affordable rates is to compare quotes from various companies.
- Online quotes might not be available; be prepared to call companies.
- Customizable policy options available to cater to individual needs.
Remember, while insurance might seem optional, it provides invaluable peace of mind against potential financial setbacks.
Choosing the Ideal Texas Homeowners Insurance Policy:
Choosing the Ideal Texas Homeowners Insurance Policy:
The apt insurance policy largely hinges on your home type, repair or rebuilding costs, and the worth of your belongings. It’s often a smart move to opt for the most robust protection within your budget. This is especially true if you haven’t set aside a significant emergency fund. Though a comprehensive policy with a lower deductible might require higher premiums, it ensures quick recovery after a substantial loss.
As your savings grow, you might consider increasing your deductible to decrease your premium. But here’s a pro tip: sometimes, a $1,000 deductible isn’t much pricier than a $5,000 one. In such instances, the minimal extra expense can prove invaluable in the event of a large claim.
The location of your mobile home, particularly the zip code in Texas, is a significant factor.
The location of your mobile home, particularly the zip code in Texas, is a significant factor.
You Need: The HO-7: Texas Mobile Home Form
You Need: The HO-7: Texas Mobile Home Form
- For Texas residents who own a mobile home, the HO-7 insurance form is crucial.
- This insurance covers both your dwelling and personal property.
- The HO-7 offers comparable coverage to the HO-3 policy.
- One thing to remember: if you plan on moving your mobile home, the HO-7 doesn’t always cover it while in transit. You may need to consider supplemental insurance in such cases.
What Does an HO-7 Policy Cover?
Type of Homes: Mobile or manufactured homes (trailers, single/double-wide mobile homes, RVs, modular homes, etc.).
Property (Dwelling & Other Structures)
Contents (Personal Property)
Dwelling & Other Structures
Personal Property
Valuable Items
Liability
Loss of Use
Medical Payments
What Does an HO-7 Policy NOT Cover?
Personal property damage that doesn't fit the named perils. Exclusions include:
- Floods
- Hurricanes
- Mold (Limited Coverage Might be Possible to Add)
- Earthquakes (Separate Policy Might be Available)
- Vandalism to Vacant Dwellings
- Wear and Tear
- Damage From Pets
- Intentional Acts
- Neglect
- Government Actions
Understand The HO-3: Texas Special Form
The HO-3 policy is the predominant homeowners insurance in Texas. It offers open-peril coverage for homes and related structures, covering all damages unless specifically excluded. Exclusions typically include:
- Earthquakes
- Floods
- Damage from insects & vermin
- Wear, neglect, or intentional damage
- Wind/hail damage to trees
- Vacancies, continuous water leaks
- Sewer backups, acts of war
- Certain mold cases
Additional Insurance Policy Options:
Even if you’ve chosen the HO-7 or another base form for your policy, you might still want to contemplate additional coverage for specific scenarios. Here are some prevalent options:
Texas DP-1 Insurance
Texas DP-3 Insurance
Personal Umbrella Policy
Scheduled Personal Property Coverage
Water Backup Coverage
Unmitigated Disasters
Choosing the Right Mobile Home Insurance for Pearland, TX.
Weather Risks:
Hurricanes and Extreme Heat
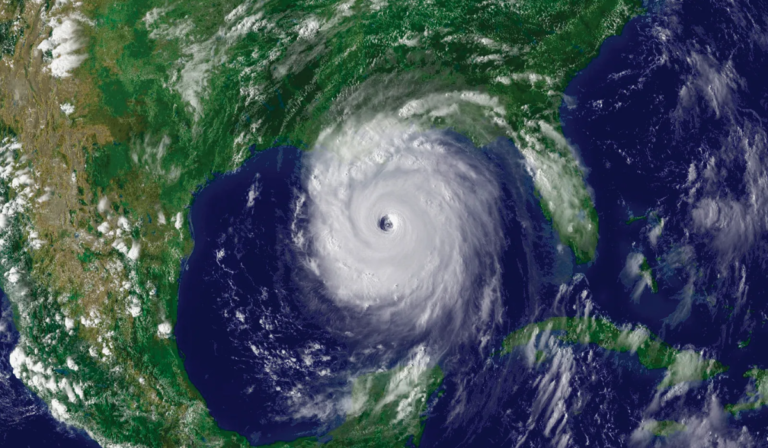
Description: Hurricanes: These tropical cyclones bring heavy rain, strong winds, and storm surges. The hurricane season in Pearland runs from June to November. Extreme Heat: In the summer, temperatures can soar, leading to heatwaves. Implications for Mobile Home & RV Owners: Damage from High Winds and Flooding: Mobile homes and RVs are vulnerable to damage from the high winds and flooding brought by hurricanes. Proper anchoring and preparation are essential. Heat Exposure: The limited insulation in mobile homes and RVs can mean interiors become uncomfortably hot, increasing the risk of heat-related illnesses.
Winter Storms
Description: Severe winter weather can bring freezing temperatures, ice, and snow. Even in Texas, where winters are generally milder, hard freezes can occur. Implications for Mobile Home & RV Owners: Pipe Damage: The plumbing systems in mobile homes and RVs are often more exposed, making them prone to freezing and bursting in cold weather. Inadequate Heating: These dwellings might lack sufficient heating, making it crucial for owners to have backup heating sources and adequate insulation.
Flooding
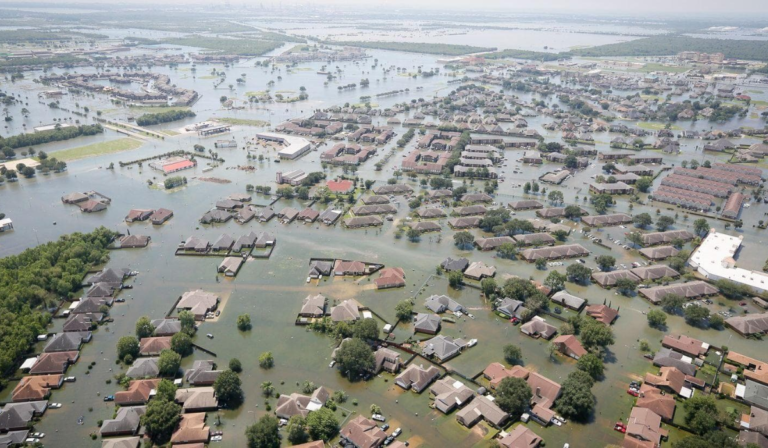
Pearland is susceptible to flooding year-round, exacerbated by heavy rains from various types of storms, including hurricanes. Implications for Mobile Home & RV Owners: Water Damage: Flooding can result in significant damage to the structures and contents of mobile homes and RVs. Evacuation Challenges: Evacuating a mobile home park or moving an RV in time can be difficult, emphasizing the importance of early warning and prompt action. Action Steps for Pearland Residents: Develop an Emergency Plan Sign Up for E-Alerts Follow Local Guidance Prepare Your Dwelling
We do insurance better. And here’s how.
- Save an average of $250 per year
- File a claim in 3 minutes
- Easily manage your policy online
- Skip the faxing, long paperwork, and unnecessary phone calls
- Get support from an American-based team
Are you in Pearland, TX, looking for mobile home insurance
Choice of 6 insurance coverage in Pearland, TX.
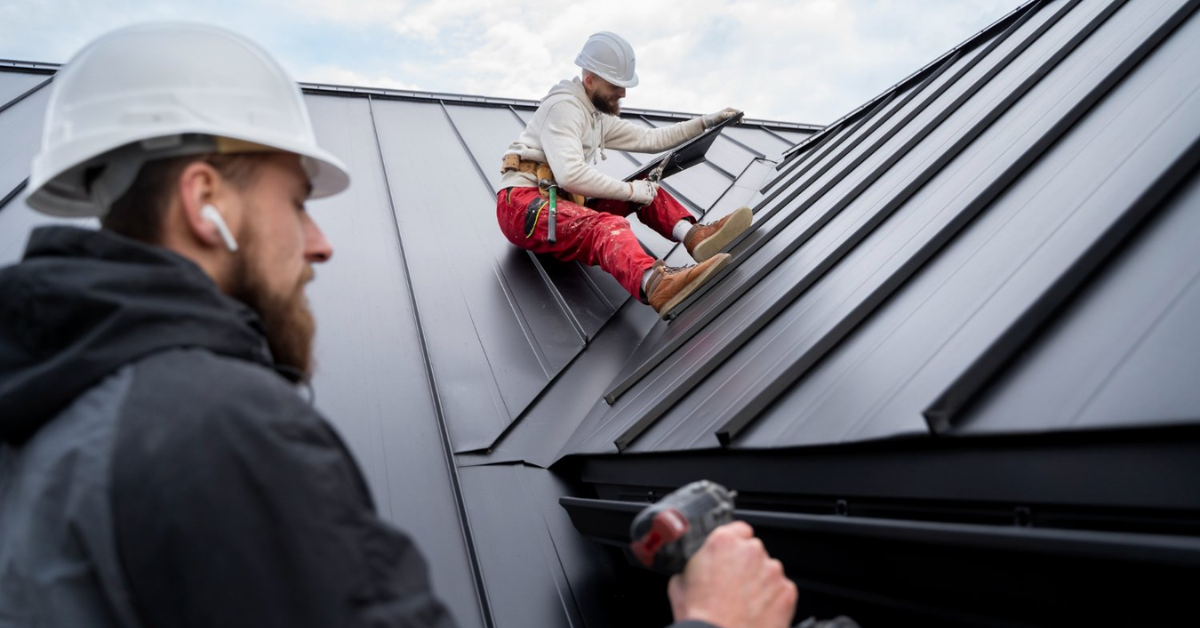
Matching Siding/Roof
What it is: Guarantees that if part of your siding or roof is damaged, the replaced section will match the existing, undamaged areas. Why it's needed: Aesthetic consistency is important for home value, and mismatched repairs can be visually unappealing.
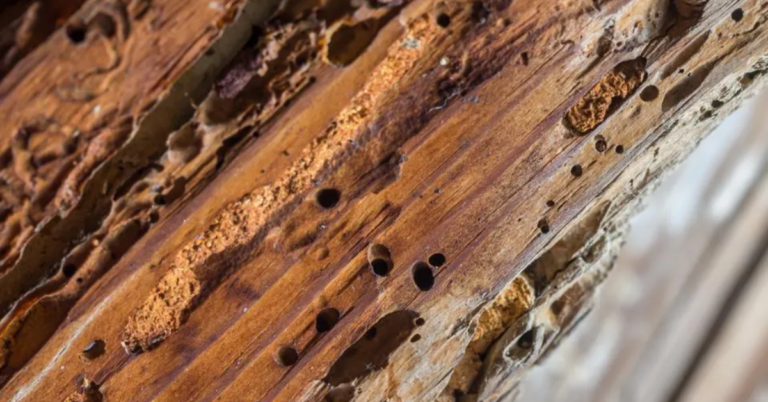
Pest Damage
What it is: Coverage against damages caused by pests like termites, rodents, etc. Why it's needed: Pest damage can be expensive to repair and isn't always covered in standard policies.
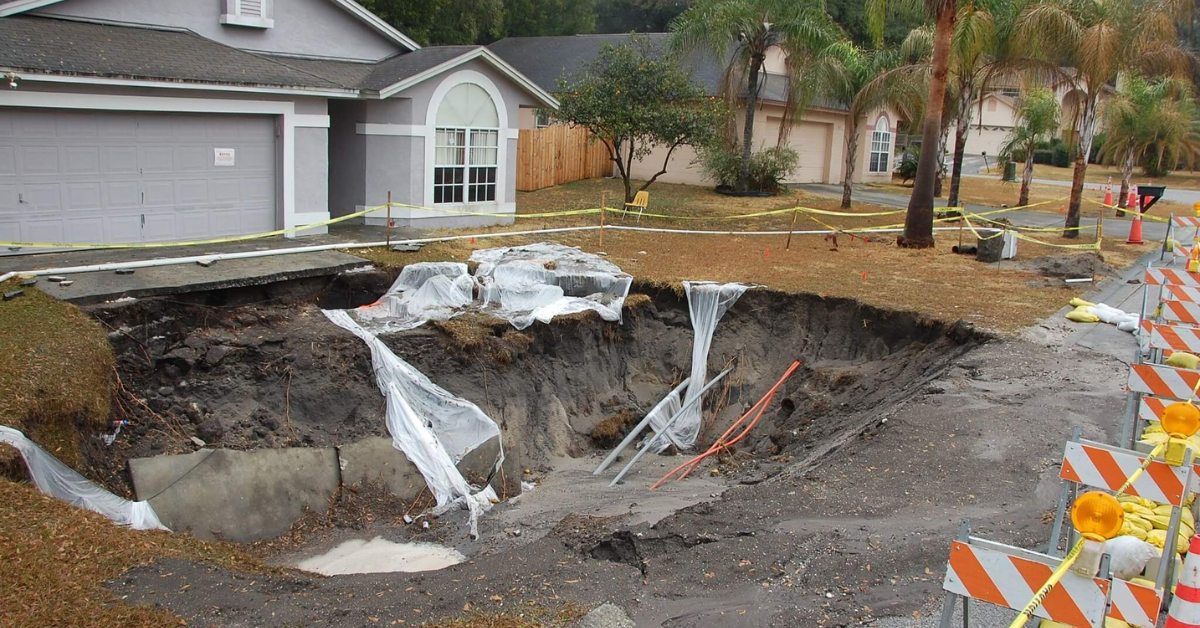
High Deductible Waiver for Catastrophic Ground Cover Collapse
What it is: The deductible is waived if there's a catastrophic ground cover collapse. Why it's needed: In areas prone to such events, this can provide significant financial relief.
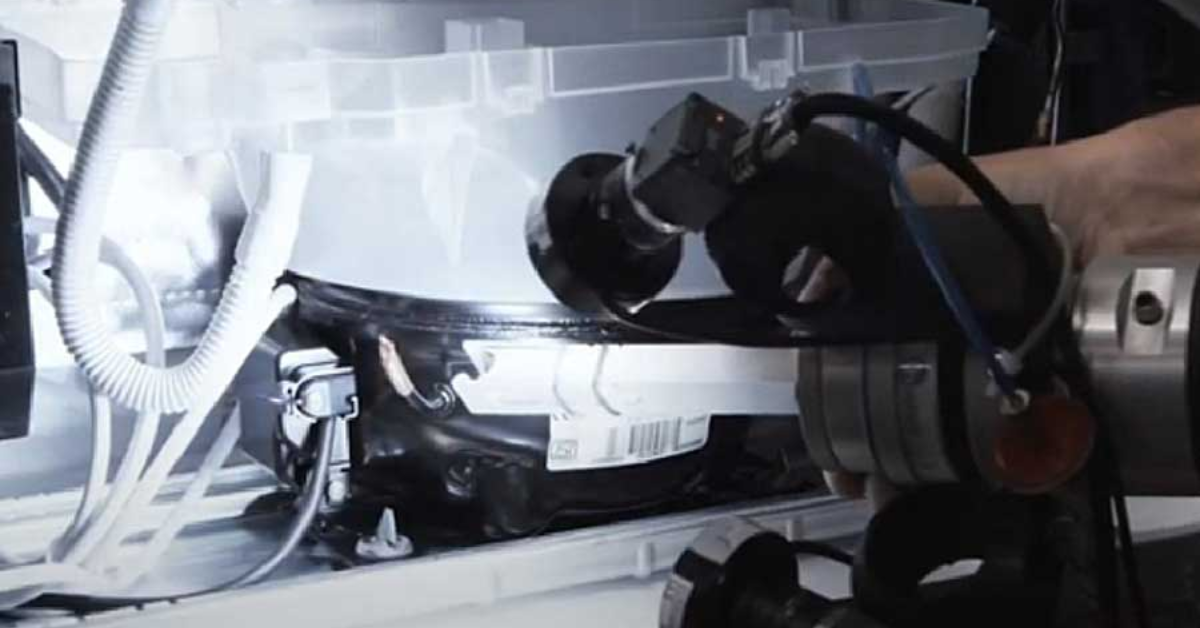
Appliance Leakage
What it is: Coverage for damages specifically caused by leaks from appliances. Why it's needed: Appliances can sometimes malfunction, leading to expensive water damages.
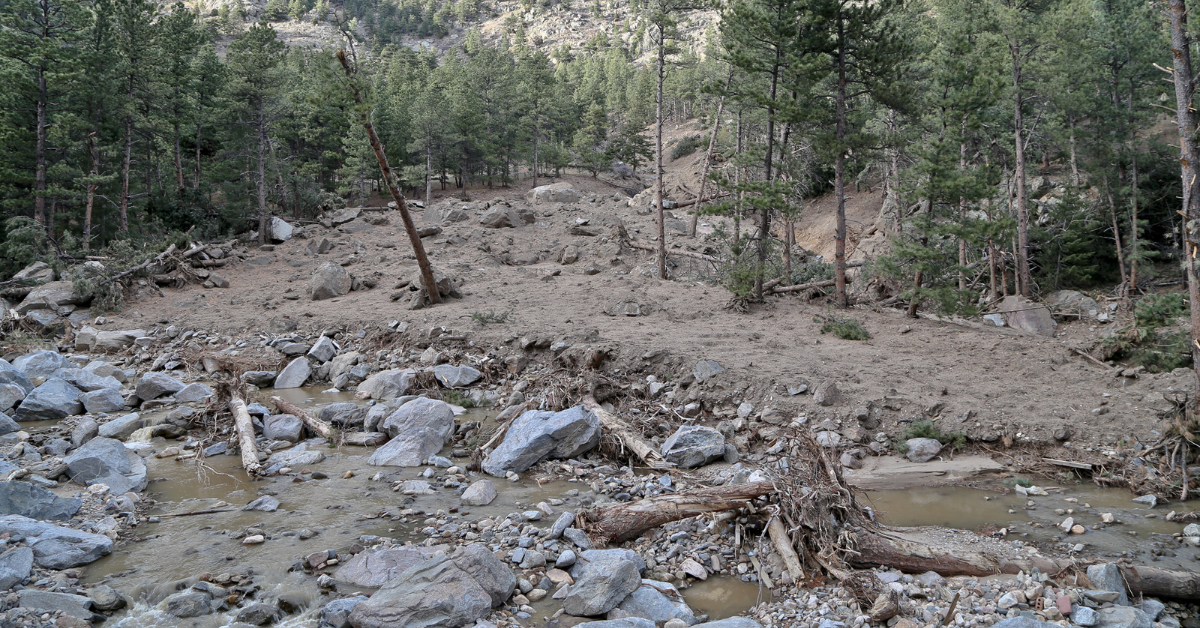
Mudflow Protection
What it is: Protection against damage caused by mudflow. Why it's needed: In areas prone to heavy rains or near mountains, mudflows can pose a significant risk.
Windstorm and Hail Coverage
What it is: Protects against damages from windstorms and hail. Why it's needed: Especially vital in regions prone to strong winds or frequent hailstorms.
Mobile Home Facts : Texas
Treatment of Manufactured Home as Real Property:
- Once a “real property election” for a manufactured home is completed, the home is deemed as real property.
- This status remains unless the home is moved, the election changes, or the property’s use alters.
- Once a statement of ownership and location is given by the department, it’s final. Changes can only be made if all parties agree, or specific procedures are followed.
- If taking responsibility for a Statement of Ownership, ensure all housing department steps are followed, including necessary notifications.
According to the Texas Underwriting Manual TX: 12.24:
- 12.24.3: Any manufactured housing unit on the property isn’t included in the land described in this commitment or policy.
- 12.24.4: Upon a lender’s request and payment as specified in R-11(e), the T-31 and/or T-31.1 Endorsements can be issued; T-31.1 can be given to both the owner and the lender.
Learn about Texas Homeowner Assistance: Two Vital Programs!
Texas residents who are struggling with home-related expenses have two vital assistance programs available: the Texas Homeowner Assistance Program due to the COVID-19 pandemic and the Homeowner Assistance Program (HAP) following Hurricane Harvey.
Treatment of Manufactured Home as Real Property:
Purpose: Support homeowners impacted by Hurricane Harvey to repair, rebuild, and enhance their homes.
Services Offered: Financial support for affected homeowners.
Homeowner Assistance Program (HAP):
Purpose: Support homeowners impacted by Hurricane Harvey to repair, rebuild, and enhance their homes.
Services Offered: Home repairs and rehabilitation I Home reconstruction I Enhancements for better resilience against natural disasters I Elevating homes above flood levels along with reconstruction aid I Temporary relocation aid
Residents are encouraged to assess their eligibility and take advantage of these programs to secure and improve their homes.
The Texas Coastal Insurance Pool (TCIP), formerly known as the Texas Windstorm Insurance Association (TWIA), is a vital insurance entity designed to protect homeowners in the Texas coastal regions. Established in the face of limited private insurance options, the TCIP provides wind and hail coverage to properties located in certain parts of Texas’s seacoast territory.
Texas Coastal Property Insurance Pool Programs!
Key Features:
Rates:
Inland of the Intracoastal Canal $2.50 per $100 coverage 42 Effective October 1, 2008 Seaward of the Intracoastal Canal $5.00 per $100 coverage
Eligibility for TWIA:
A mobile home located in a designated catastrophe area that meets the following criteria is eligible to be insured under the T.W.I.A. Dwelling Policy with Form No. TWIA-411, Conversion to TWIA Manufactured Home Policy attached to the policy.
The mobile home complies with the definition of manufactured home under the rules and regulations of the Texas Department of Housing and Community Affairs (TDHCA). Criteria 2 The mobile home is occupied solely as a one or two family residence. Criteria 3Additions to Mobile Homes:
- A site-built addition attached to a mobile home will rate as part of the mobile home.
- A building certification from the Texas Department of Insurance is required for the site-built addition.
- Separate structures (not physically attached to the mobile home) are not eligible for insurance under the T.W.I.A. Dwelling Policy with Form No. TWIA411, Conversion to TWIA Manufactured Home Policy attached to the policy. Refer to eligibility requirements for insurance under the Association’s Dwelling Policy.
Deductibles:
- The following deductibles are mandatory under the T.W.I.A. Dwelling Policy with Form No. TWIA-411, Conversion to TWIA Manufactured Home Policy attached to the policy. a. Homes located inland of the Intracoastal Canal: 1% of limit of liability with a $250 minimum (TWIA Form No. 570) b. Homes located seaward of the Intracoastal Canal: 2% of the limit of liability with a $250 minimum (TWIA Form No. 575)
- Deductibles apply separately to the home and household goods items on the policy.
Limit of Liability:
The maximum limit of liability for a mobile home, including any site-built additions attached to the home, and household goods is $84,000.
Policy Forms & Endorsements:
The following policy form is to be used: T.W.I.A. Dwelling Policy with Form No. TWIA-411, Conversion to TWIA Manufactured Home Policy attached to the policy
Know Your Rights!
- Texas Tenant Advisor
- Texas Law Help – Manufactured Housing Owner’s Rights
- Property Code TITLE 8. Landlord and Tenant Chapter 94. Manufactured Home Tenancies
- Property Code TITLE 8. Landlord and Tenant Chapter 92. Manufactured Home Tenancies
- Landlords and Tenants Guide for Manufactured Home Communities
- Texas Manufactured Housing Standards Act
- Legal Q&A By Sarah Tompkins, TML Legal Counsel
- Texas Law Help – What To Know Before You Buy a Manufactured/Mobile Home
- Homeowner Assistance Program
- Manufactured Housing Single-Trip Permits
- Mobile Home Insurance in Texas
- Texas Department of Insurance – Consumer Guides: Homeowner’s Insurance Guide
- Consumer Bill of Rights
- Texas Windstorm Insurance Association
- Texas Windstorm Help Guide
- Texas Law Help – Manufactured Housing and Disasters
Additional Policy Riders for Mobile Home Insurance in Texas:
Adding policy options to a basic insurance plan is a common practice in the mobile home insurance industry. While the events covered in mobile home policies are similar across all states, additional coverage options, known as add-ons, endorsements, and riders, may vary depending on your location and insurance provider. Each of these options comes at an additional cost that can be customized according to your needs.
Provides protection against flood-related damages, excluding waterline or sewer backups. Average annual cost: $700. Earthquake InsuranceAdding any rider will increase your premiums, influenced by location, risk profile, chosen coverage, and deductible. Riders can be added during initial policy purchase, at renewal, or anytime during the policy period. Some carriers might not offer all endorsements, so shopping around might be necessary.