
Insurance guides
Protecting Your Manufactured Home in Grand Prairie, TX.
Disclaimer: Data Accuracy and Sources
The data in the Covertree Resources section is from publicly available sources last updated in December 2022. We provide source links for verification. However, we can’t guarantee accuracy. Rely on this data at your own discretion. For specific advice, consult professionals.
Welcome to Grand Prairie, Texas -a mosaic of history, culture, and recreation! Situated between the vibrant cities of Dallas and Fort Worth, Grand Prairie is a nexus of culture, history, and natural beauty, providing a unique blend of the Texan experience. Its strategic location has shaped its historical importance and modern development, making it a key player in the evolution of the North Texas region.
Grand Prairie’s history dates back to 1863 when Alexander McRae Dechman, a settler from Birdville, traded his oxen and wagon for land here, envisioning the growth potential of the region. As railroads proliferated in the late 19th century, so did Grand Prairie’s prominence as a transport hub. The introduction of the Texas Interurban Railway in the early 20th century further integrated Grand Prairie into the rapidly expanding Dallas-Fort Worth metropolitan area.
Grand Prairie has played a crucial role as an industrial powerhouse, especially during World War II. It was home to the North American Aviation plant, which produced thousands of aircraft for the war effort. This historical significance has transitioned into a modern industrial prowess, with the city housing numerous corporations and distribution centers, benefiting from its prime location in the heart of DFW.
Trinity River winds its way through Grand Prairie, providing ample opportunities for fishing, kayaking, and scenic walks. The city is also home to the expansive Joe Pool Lake, offering a getaway for those who enjoy boating, camping, and picnicking. For family-friendly fun, there’s Epic Waters Indoor Waterpark, a massive, year-round aquatic wonderland, and Lynn Creek Park with its beautiful beach and marina. For a dose of nature, the nearby Cedar Hill State Park offers miles of trails and bird-watching opportunities.
The city has not just rested on its natural laurels; its man-made entertainment venues are equally compelling. The historic Uptown Theater, built in the 1950s, has been restored to its former glory and offers an intimate setting for concerts and plays. The annual Main Street Fest is a celebration of the local community, bringing together residents for a weekend of music, food, and art. Additionally, the Grand Prairie Farmers Market is a testament to the city’s agricultural roots, providing fresh produce and artisanal products throughout the year.
Understanding Mobile Home Insurance In Texas.
Do I Need Mobile Home Insurance in Texas?
Do I Need Mobile Home Insurance in Texas?
- Optional, but often required by lenders and mobile home communities.
- Lenders can’t mandate coverage that surpasses home and content replacement value.
- Strongly recommended for financial protection against damages.
Texas Mobile Home Insurance Costs Explained
Texas Mobile Home Insurance Costs Explained
Mobile home insurance is essential for safeguarding your most valuable asset. Prices in Texas typically range from $250 to $1,300 annually, influenced by various factors. Deciding between actual cash value and replacement cost coverage will also impact both premiums and compensation amounts in case of a claim.
Insurance rates are influenced by:
Insurance rates are influenced by:
- Geographic area (land value, crime rate, and environmental threats).
- Home’s value, size, and location.
- Home’s age.
- Chosen liability coverage.
- Desired personal property coverage amount.
- Selected deductible.
- Actual Cash Value: Compensates the current value of the home, accounting for depreciation. *
- Replacement Cost: Covers the cost of a new, similar home regardless of the original home’s age or previous value. **
* e.g. A five-year-old home bought for $50,000 but now worth $35,000 will be compensated at $35,000.
** Typically has higher premiums but offers more compensation during a claim.
Unique Considerations for Texas Mobile Home Insurance!
Unique Considerations for Texas Mobile Home Insurance!
- Wind and hail coverage may be excluded for homes near the coast.
- Purchase flood insurance via the National Flood Insurance Program if difficult to find in the private market.
- For wind and hail coverage, consider Texas Windstorm Insurance Association (TWIA).
Mobile Home Insurance Coverage in Texas:
Mobile Home Insurance Coverage in Texas:
- Dwelling coverage: Protection for permanent structures attached to the home.
- Personal property: Covers belongings if damaged or stolen.
- Liability protection: Provides financial protection in case a guest is injured on your property.
- Other structures: Coverage for free-standing structures on your property, e.g., sheds or fences.
- Additional living expenses: Covers costs if home becomes uninhabitable due to a covered loss.
Filing a Mobile Home Insurance Claim in Texas:
Filing a Mobile Home Insurance Claim in Texas:
- Insurance companies must acknowledge the claim within 15 days.
- Companies have 15 business days to accept or deny a claim, with potential for extensions in the event of major disasters.
- Possible 45-day decision timeframe if reasons are provided for delay.
- Failure to adhere to deadlines could result in the company being sued for the claim amount, interest, and legal fees.
Tips for Purchasing Mobile Home Insurance in Texas:
Tips for Purchasing Mobile Home Insurance in Texas:
- Mobile home insurance is often pricier than standard homeowners insurance.
- Best way to get affordable rates is to compare quotes from various companies.
- Online quotes might not be available; be prepared to call companies.
- Customizable policy options available to cater to individual needs.
Remember, while insurance might seem optional, it provides invaluable peace of mind against potential financial setbacks.
Choosing the Ideal Texas Homeowners Insurance Policy:
Choosing the Ideal Texas Homeowners Insurance Policy:
The apt insurance policy largely hinges on your home type, repair or rebuilding costs, and the worth of your belongings. It’s often a smart move to opt for the most robust protection within your budget. This is especially true if you haven’t set aside a significant emergency fund. Though a comprehensive policy with a lower deductible might require higher premiums, it ensures quick recovery after a substantial loss.
As your savings grow, you might consider increasing your deductible to decrease your premium. But here’s a pro tip: sometimes, a $1,000 deductible isn’t much pricier than a $5,000 one. In such instances, the minimal extra expense can prove invaluable in the event of a large claim.
The location of your mobile home, particularly the zip code in Texas, is a significant factor.
The location of your mobile home, particularly the zip code in Texas, is a significant factor.
You Need: The HO-7: Texas Mobile Home Form
You Need: The HO-7: Texas Mobile Home Form
- For Texas residents who own a mobile home, the HO-7 insurance form is crucial.
- This insurance covers both your dwelling and personal property.
- The HO-7 offers comparable coverage to the HO-3 policy.
- One thing to remember: if you plan on moving your mobile home, the HO-7 doesn’t always cover it while in transit. You may need to consider supplemental insurance in such cases.
What Does an HO-7 Policy Cover?
Type of Homes: Mobile or manufactured homes (trailers, single/double-wide mobile homes, RVs, modular homes, etc.).
Property (Dwelling & Other Structures)
Contents (Personal Property)
Dwelling & Other Structures
Personal Property
Valuable Items
Liability
Loss of Use
Medical Payments
What Does an HO-7 Policy NOT Cover?
Personal property damage that doesn't fit the named perils. Exclusions include:
- Floods
- Hurricanes
- Mold (Limited Coverage Might be Possible to Add)
- Earthquakes (Separate Policy Might be Available)
- Vandalism to Vacant Dwellings
- Wear and Tear
- Damage From Pets
- Intentional Acts
- Neglect
- Government Actions
Understand The HO-3: Texas Special Form
The HO-3 policy is the predominant homeowners insurance in Texas. It offers open-peril coverage for homes and related structures, covering all damages unless specifically excluded. Exclusions typically include:
- Earthquakes
- Floods
- Damage from insects & vermin
- Wear, neglect, or intentional damage
- Wind/hail damage to trees
- Vacancies, continuous water leaks
- Sewer backups, acts of war
- Certain mold cases
Additional Insurance Policy Options:
Even if you’ve chosen the HO-7 or another base form for your policy, you might still want to contemplate additional coverage for specific scenarios. Here are some prevalent options:
Texas DP-1 Insurance
Texas DP-3 Insurance
Personal Umbrella Policy
Scheduled Personal Property Coverage
Water Backup Coverage
Unmitigated Disasters
Choosing the Right Mobile Home Insurance for Grand Prairie, TX.
Severe Thunderstorms, Hail & Tornados
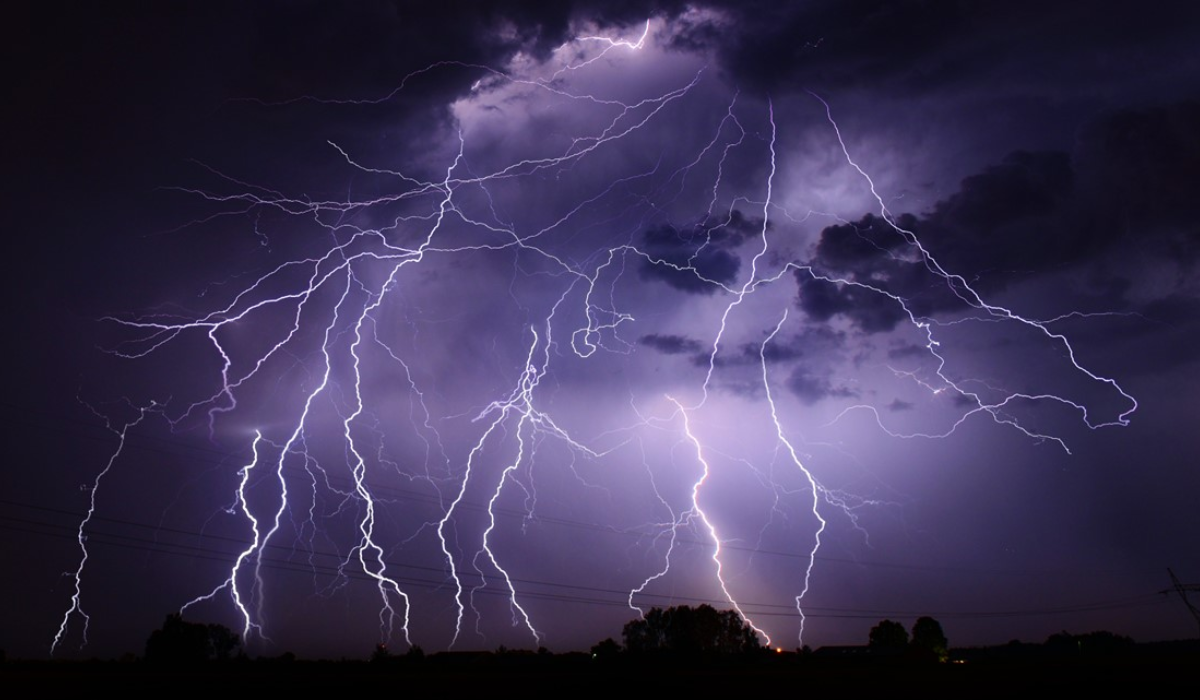
Grand Prairie, positioned in the heart of Texas, is no stranger to the wrath of severe thunderstorms. These storms, which can occur at any time of the year, though predominantly in the spring, bring along heavy rain, fierce winds, and the roar of thunder. Accompanying the rain and thunder might be hail - frozen rain droplets falling at high velocities, posing threats to property and personal safety. It's crucial to remember that the presence of thunder indicates potential lightning strikes. Seeking shelter immediately, avoiding metal objects, and waiting for a good 30 minutes post the last clap of thunder is recommended. Another menacing offshoot of severe storms is tornadoes - violent whirlwinds capable of causing substantial damage and loss. Grand Prairie residents need to be vigilant, especially when tornado warnings are issued. Immediate action like seeking shelter in the most interior room of a building, avoiding windows, and never attempting to outrun a tornado in a vehicle can be life-saving.
Flooding Risks
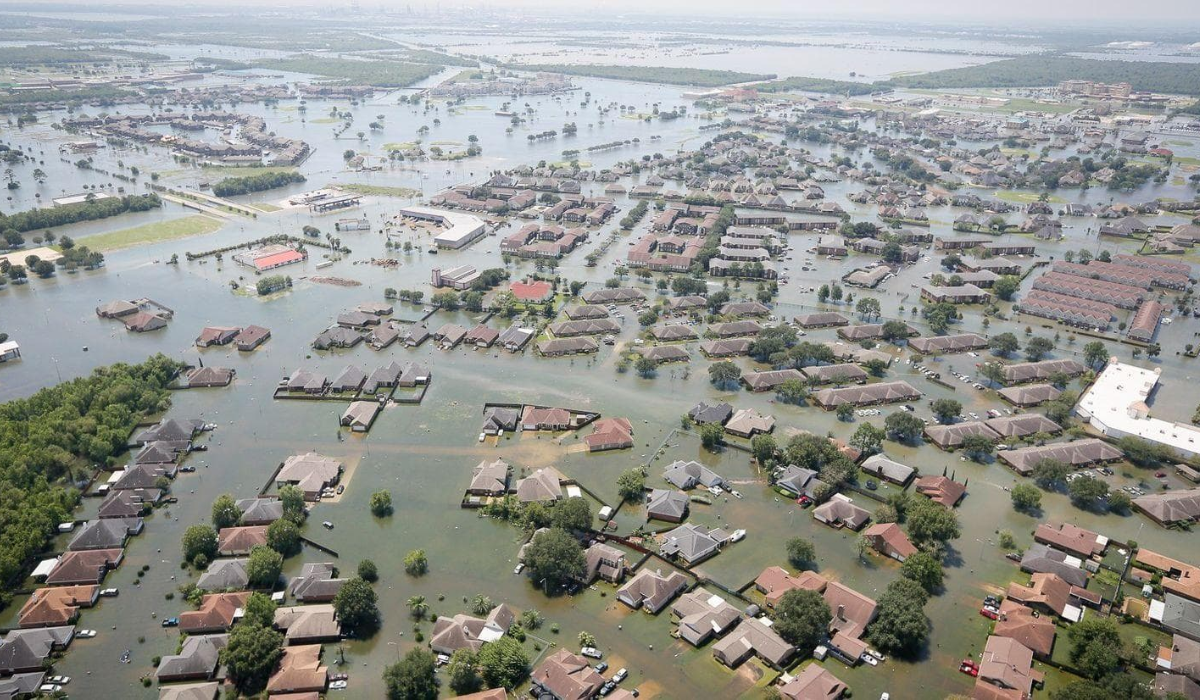
Among the myriad of natural hazards, flooding stands out as the most deadly in Grand Prairie. Flash floods, which form and move swiftly, pose an instantaneous risk, while gradual flooding provides a tad bit more time to react. Yet, both can be disastrous, given the mere six inches of moving water has the force to knock an adult off their feet. Residents are constantly reminded of the golden rule - "Turn around, don’t drown!" Evacuating low-lying areas, avoiding already flooded regions, and being alert about the vehicular stalling in high waters can prevent catastrophes. Residents in flood-prone areas might also consider checking their eligibility for the National Flood Insurance Program to safeguard their properties.
Extreme Temperatures (Heatwaves/Cold Snaps)
The scorching Texan sun can lead to extreme heat periods, especially when coupled with high humidity levels. Such conditions are not just uncomfortable but can result in severe heat-related ailments. It's essential to stay hydrated, use sunscreen, and if possible, remain indoors during peak heat hours. Conversely, while snow can paint a picturesque winter wonderland, the hazards it brings cannot be overlooked. Freezing rain, especially, forms a layer of slippery ice on roads and sidewalks, making mobility a challenge. Grand Prairie residents are advised to wear warm clothing, be cautious while driving, especially on overpasses and bridges, and ensure proper functioning of all heating devices at home to stay safe during such times.
We do insurance better. And here’s how.
- Save an average of $250 per year
- File a claim in 3 minutes
- Easily manage your policy online
- Skip the faxing, long paperwork, and unnecessary phone calls
- Get support from an American-based team
Are you in Grand Prairie, TX, looking for mobile home insurance
Choice of 6 insurance coverage in Grand Prairie, TX.
Accidental Damage
What it is: Coverage for unintentional direct physical losses not specifically excluded or limited.
Why it's needed: Accidents happen, and this ensures unexpected damages are covered.
Scheduled Personal Property Coverage
What it is: Increases the coverage amount for specific, valuable personal property items.
Why it's needed: Standard policies might not fully cover high-value items. This customization ensures adequate coverage.
Extended Replacement Cost Coverage:
What it is: Boosts the limits of dwelling coverage, ensuring homes are rebuilt using similar materials.
Why it's needed: Protects against escalating building costs, ensuring homes are fully restored.
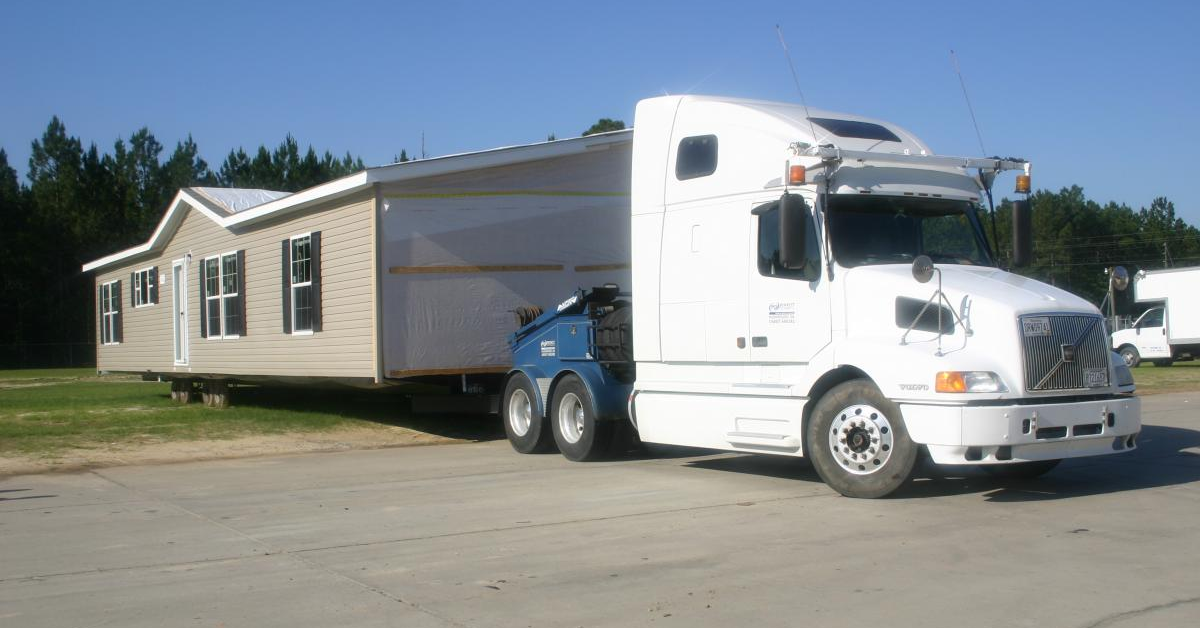
In Motion
What it is: Coverage specifically designed for mobile homeowners who frequently relocate their homes, offering protection against damages or losses that might occur while the manufactured home is being transported or is "in motion."
Why it's needed: Provides financial security against various risks such as accidents, adverse weather conditions, or other unforeseen events when transporting a mobile home.
Loss of Rent Coverage
What it is: If a mobile home is rented out and becomes uninhabitable due to a covered event, this provides compensation for lost rental income.
Why it's needed: For property owners who rely on rental income, it ensures financial stability after unexpected events.
Cyber Security Coverage
What it is: Protection against risks related to digital threats, like hacking, data breaches, or ransomware.
Why it's needed: As homeowners increasingly rely on smart devices and home networks, they become targets for cyber-attacks, making this coverage ever more essential.
Mobile Home Facts : Texas
Treatment of Manufactured Home as Real Property:
- Once a “real property election” for a manufactured home is completed, the home is deemed as real property.
- This status remains unless the home is moved, the election changes, or the property’s use alters.
- Once a statement of ownership and location is given by the department, it’s final. Changes can only be made if all parties agree, or specific procedures are followed.
- If taking responsibility for a Statement of Ownership, ensure all housing department steps are followed, including necessary notifications.
According to the Texas Underwriting Manual TX: 12.24:
- 12.24.3: Any manufactured housing unit on the property isn’t included in the land described in this commitment or policy.
- 12.24.4: Upon a lender’s request and payment as specified in R-11(e), the T-31 and/or T-31.1 Endorsements can be issued; T-31.1 can be given to both the owner and the lender.
Learn about Texas Homeowner Assistance: Two Vital Programs!
Texas residents who are struggling with home-related expenses have two vital assistance programs available: the Texas Homeowner Assistance Program due to the COVID-19 pandemic and the Homeowner Assistance Program (HAP) following Hurricane Harvey.
Treatment of Manufactured Home as Real Property:
Purpose: Support homeowners impacted by Hurricane Harvey to repair, rebuild, and enhance their homes.
Services Offered: Financial support for affected homeowners.
Homeowner Assistance Program (HAP):
Purpose: Support homeowners impacted by Hurricane Harvey to repair, rebuild, and enhance their homes.
Services Offered: Home repairs and rehabilitation I Home reconstruction I Enhancements for better resilience against natural disasters I Elevating homes above flood levels along with reconstruction aid I Temporary relocation aid
Residents are encouraged to assess their eligibility and take advantage of these programs to secure and improve their homes.
Texas Coastal Property Insurance Pool Programs!
The Texas Coastal Insurance Pool (TCIP), formerly known as the Texas Windstorm Insurance Association (TWIA), is a vital insurance entity designed to protect homeowners in the Texas coastal regions. Established in the face of limited private insurance options, the TCIP provides wind and hail coverage to properties located in certain parts of Texas’s seacoast territory.
Key Features:
Rates:
Inland of the Intracoastal Canal $2.50 per $100 coverage 42 Effective October 1, 2008 Seaward of the Intracoastal Canal $5.00 per $100 coverage
Eligibility for TWIA:
A mobile home located in a designated catastrophe area that meets the following criteria is eligible to be insured under the T.W.I.A. Dwelling Policy with Form No. TWIA-411, Conversion to TWIA Manufactured Home Policy attached to the policy.
The mobile home complies with the definition of manufactured home under the rules and regulations of the Texas Department of Housing and Community Affairs (TDHCA). Criteria 2 The mobile home is occupied solely as a one or two family residence. Criteria 3Additions to Mobile Homes:
- A site-built addition attached to a mobile home will rate as part of the mobile home.
- A building certification from the Texas Department of Insurance is required for the site-built addition.
- Separate structures (not physically attached to the mobile home) are not eligible for insurance under the T.W.I.A. Dwelling Policy with Form No. TWIA411, Conversion to TWIA Manufactured Home Policy attached to the policy. Refer to eligibility requirements for insurance under the Association’s Dwelling Policy.
Deductibles:
- The following deductibles are mandatory under the T.W.I.A. Dwelling Policy with Form No. TWIA-411, Conversion to TWIA Manufactured Home Policy attached to the policy. a. Homes located inland of the Intracoastal Canal: 1% of limit of liability with a $250 minimum (TWIA Form No. 570) b. Homes located seaward of the Intracoastal Canal: 2% of the limit of liability with a $250 minimum (TWIA Form No. 575)
- Deductibles apply separately to the home and household goods items on the policy.
Limit of Liability:
The maximum limit of liability for a mobile home, including any site-built additions attached to the home, and household goods is $84,000.
Policy Forms & Endorsements:
The following policy form is to be used: T.W.I.A. Dwelling Policy with Form No. TWIA-411, Conversion to TWIA Manufactured Home Policy attached to the policy
Know Your Rights!
- Texas Tenant Advisor
- Texas Law Help – Manufactured Housing Owner’s Rights
- Property Code TITLE 8. Landlord and Tenant Chapter 94. Manufactured Home Tenancies
- Property Code TITLE 8. Landlord and Tenant Chapter 92. Manufactured Home Tenancies
- Landlords and Tenants Guide for Manufactured Home Communities
- Texas Manufactured Housing Standards Act
- Legal Q&A By Sarah Tompkins, TML Legal Counsel
- Texas Law Help – What To Know Before You Buy a Manufactured/Mobile Home
- Homeowner Assistance Program
- Manufactured Housing Single-Trip Permits
- Mobile Home Insurance in Texas
- Texas Department of Insurance – Consumer Guides: Homeowner’s Insurance Guide
- Consumer Bill of Rights
- Texas Windstorm Insurance Association
- Texas Windstorm Help Guide
- Texas Law Help – Manufactured Housing and Disasters
Additional Policy Riders for Mobile Home Insurance in Texas:
Adding policy options to a basic insurance plan is a common practice in the mobile home insurance industry. While the events covered in mobile home policies are similar across all states, additional coverage options, known as add-ons, endorsements, and riders, may vary depending on your location and insurance provider. Each of these options comes at an additional cost that can be customized according to your needs.
Provides protection against flood-related damages, excluding waterline or sewer backups. Average annual cost: $700. Earthquake InsuranceAdding any rider will increase your premiums, influenced by location, risk profile, chosen coverage, and deductible. Riders can be added during initial policy purchase, at renewal, or anytime during the policy period. Some carriers might not offer all endorsements, so shopping around might be necessary.