
Insurance guides
Protecting Your Manufactured Home in Houston, TX.
Disclaimer: Data Accuracy and Sources
The data in the Covertree Resources section is from publicly available sources last updated in December 2022. We provide source links for verification. However, we can’t guarantee accuracy. Rely on this data at your own discretion. For specific advice, consult professionals.
Welcome to Houston, Texas -a tapestry of history, culture, and innovation! Located in the southeastern quadrant of Texas, the sprawling metropolis of Houston stands as a testament to humanity’s enduring spirit, innovation, and undying love for community. The city’s skyline, punctuated with gleaming skyscrapers, hints at the energy and ambition that courses through its streets. Yet, beneath the modern façade lies a rich tapestry of history and culture, waiting to be explored.
Established in 1836 by the Allen brothers and named after General Sam Houston, the city’s beginnings are deeply rooted in the fight for Texan independence. Today, it stands as the fourth-largest city in the U.S., but its rapid growth has not come at the expense of its history or unique character.
One of Houston’s most remarkable claims to fame is its role in space exploration. “Houston” was, after all, the first word spoken from the moon. The Johnson Space Center and Space Center Houston serve as both a tribute to the nation’s astronautical achievements and a beacon for future explorers.
But the city’s wonders don’t stop at the stars. Houston is home to a thriving arts scene, boasting theaters that host Broadway hits and galleries showcasing local and global masterpieces. The Museum District alone houses 19 museums, each resonating with its own unique stories and treasures.
While Houston’s legacy in space exploration often takes center stage, the city’s on-the-ground offerings are as vast and varied as the Texan landscape itself. From the tranquility of its green spaces to the hustle of its shopping districts, there’s no shortage of adventures to embark on.
Be sure to visit:
Theater District: Houston is one of the few U.S. cities with permanent professional resident companies in all major performing arts disciplines. The Wortham Theater Center, Alley Theatre, and the Hobby Center for the Performing Arts are just a few venues where you can enjoy world-class performances.
Menil Collection: A free-entry museum that houses an impressive collection of 20th-century art, it’s a serene enclave in the heart of the city, complete with park-like surroundings.
Buffalo Bayou Park: This urban green space offers walking and biking trails, paddlecraft rentals, and beautiful skyline views. The underground cistern here, once a city reservoir, now hosts art installations.
Discovery Green: A vibrant 12-acre park in the heart of downtown, it offers a range of recreational activities, events, and public art pieces.
The Galleria: Texas’ largest shopping center, it’s a mecca for retail therapy enthusiasts, boasting over 400 stores and even an ice rink!
GreenStreet: A dynamic shopping and dining destination, it also offers entertainment venues, including House of Blues. The Historic Heights: A neighborhood that offers a journey back in time with its well-preserved Victorian architecture and vintage stores. Don’t miss the Heights Mercantile, an urban market district.
San Jacinto Monument: Commemorating the site of Texas’ battle for independence, this monument offers panoramic views of the city and the Ship Channel.
Downtown Aquarium: A combination of an aquarium and amusement park, it’s an ideal family destination with touch pools, a white tiger exhibit, and a Ferris wheel.
Houston Museum of Natural Science: From the wonders of space to the mysteries of ancient Egypt, this museum offers interactive exhibits sure to spark curiosity in visitors of all ages.
Did you know that Houston has more than 10,000 restaurants representing over 70 countries and American regions? Its culinary prowess is unmatched, making it a food lover’s paradise. From succulent barbecue joints to gourmet dining experiences, there’s a plate for every palate.
Nature enthusiasts aren’t left out either. The city boasts the Houston Zoo, one of the most visited zoos in the nation, and the expansive Hermann Park. The bayous that crisscross the city offer picturesque walking trails and opportunities to see urban wildlife.
Festivals, sports, shopping, music – Houston pulsates with diverse experiences. The city’s rich tapestry is woven from threads of many cultures, a melting pot of languages, traditions, and dreams. It’s a city that welcomes all, from cowboys to astronauts, artists to entrepreneurs, making it a mosaic of memories and moments.
So, whether you’re drawn to the echoes of history, the allure of space, the allure of art, or the simple joy of a shared meal, Houston offers an embrace that feels like home.
Understanding Mobile Home Insurance In Texas.
Do I Need Mobile Home Insurance in Texas?
Do I Need Mobile Home Insurance in Texas?
- Optional, but often required by lenders and mobile home communities.
- Lenders can’t mandate coverage that surpasses home and content replacement value.
- Strongly recommended for financial protection against damages.
Texas Mobile Home Insurance Costs Explained
Texas Mobile Home Insurance Costs Explained
Mobile home insurance is essential for safeguarding your most valuable asset. Prices in Texas typically range from $250 to $1,300 annually, influenced by various factors. Deciding between actual cash value and replacement cost coverage will also impact both premiums and compensation amounts in case of a claim.
Insurance rates are influenced by:
Insurance rates are influenced by:
- Geographic area (land value, crime rate, and environmental threats).
- Home’s value, size, and location.
- Home’s age.
- Chosen liability coverage.
- Desired personal property coverage amount.
- Selected deductible.
- Actual Cash Value: Compensates the current value of the home, accounting for depreciation. *
- Replacement Cost: Covers the cost of a new, similar home regardless of the original home’s age or previous value. **
* e.g. A five-year-old home bought for $50,000 but now worth $35,000 will be compensated at $35,000.
** Typically has higher premiums but offers more compensation during a claim.
Unique Considerations for Texas Mobile Home Insurance!
Unique Considerations for Texas Mobile Home Insurance!
- Wind and hail coverage may be excluded for homes near the coast.
- Purchase flood insurance via the National Flood Insurance Program if difficult to find in the private market.
- For wind and hail coverage, consider Texas Windstorm Insurance Association (TWIA).
Mobile Home Insurance Coverage in Texas:
Mobile Home Insurance Coverage in Texas:
- Dwelling coverage: Protection for permanent structures attached to the home.
- Personal property: Covers belongings if damaged or stolen.
- Liability protection: Provides financial protection in case a guest is injured on your property.
- Other structures: Coverage for free-standing structures on your property, e.g., sheds or fences.
- Additional living expenses: Covers costs if home becomes uninhabitable due to a covered loss.
Filing a Mobile Home Insurance Claim in Texas:
Filing a Mobile Home Insurance Claim in Texas:
- Insurance companies must acknowledge the claim within 15 days.
- Companies have 15 business days to accept or deny a claim, with potential for extensions in the event of major disasters.
- Possible 45-day decision timeframe if reasons are provided for delay.
- Failure to adhere to deadlines could result in the company being sued for the claim amount, interest, and legal fees.
Tips for Purchasing Mobile Home Insurance in Texas:
Tips for Purchasing Mobile Home Insurance in Texas:
- Mobile home insurance is often pricier than standard homeowners insurance.
- Best way to get affordable rates is to compare quotes from various companies.
- Online quotes might not be available; be prepared to call companies.
- Customizable policy options available to cater to individual needs.
Remember, while insurance might seem optional, it provides invaluable peace of mind against potential financial setbacks.
Choosing the Ideal Texas Homeowners Insurance Policy:
Choosing the Ideal Texas Homeowners Insurance Policy:
The apt insurance policy largely hinges on your home type, repair or rebuilding costs, and the worth of your belongings. It’s often a smart move to opt for the most robust protection within your budget. This is especially true if you haven’t set aside a significant emergency fund. Though a comprehensive policy with a lower deductible might require higher premiums, it ensures quick recovery after a substantial loss.
As your savings grow, you might consider increasing your deductible to decrease your premium. But here’s a pro tip: sometimes, a $1,000 deductible isn’t much pricier than a $5,000 one. In such instances, the minimal extra expense can prove invaluable in the event of a large claim.
The location of your mobile home, particularly the zip code in Texas, is a significant factor.
The location of your mobile home, particularly the zip code in Texas, is a significant factor.
You Need: The HO-7: Texas Mobile Home Form
You Need: The HO-7: Texas Mobile Home Form
- For Texas residents who own a mobile home, the HO-7 insurance form is crucial.
- This insurance covers both your dwelling and personal property.
- The HO-7 offers comparable coverage to the HO-3 policy.
- One thing to remember: if you plan on moving your mobile home, the HO-7 doesn’t always cover it while in transit. You may need to consider supplemental insurance in such cases.
What Does an HO-7 Policy Cover?
Type of Homes: Mobile or manufactured homes (trailers, single/double-wide mobile homes, RVs, modular homes, etc.).
Property (Dwelling & Other Structures)
Contents (Personal Property)
Dwelling & Other Structures
Personal Property
Valuable Items
Liability
Loss of Use
Medical Payments
What Does an HO-7 Policy NOT Cover?
Personal property damage that doesn't fit the named perils. Exclusions include:
- Floods
- Hurricanes
- Mold (Limited Coverage Might be Possible to Add)
- Earthquakes (Separate Policy Might be Available)
- Vandalism to Vacant Dwellings
- Wear and Tear
- Damage From Pets
- Intentional Acts
- Neglect
- Government Actions
Understand The HO-3: Texas Special Form
The HO-3 policy is the predominant homeowners insurance in Texas. It offers open-peril coverage for homes and related structures, covering all damages unless specifically excluded. Exclusions typically include:
- Earthquakes
- Floods
- Damage from insects & vermin
- Wear, neglect, or intentional damage
- Wind/hail damage to trees
- Vacancies, continuous water leaks
- Sewer backups, acts of war
- Certain mold cases
Additional Insurance Policy Options:
Even if you’ve chosen the HO-7 or another base form for your policy, you might still want to contemplate additional coverage for specific scenarios. Here are some prevalent options:
Texas DP-1 Insurance
Texas DP-3 Insurance
Personal Umbrella Policy
Scheduled Personal Property Coverage
Water Backup Coverage
Unmitigated Disasters
Choosing the Right Mobile Home Insurance for Houston, TX.
Extreme Heat and Urban Heat Islands
Increasing Temperatures: The Houston region has witnessed a notable increase in average temperatures in the last decade. There's been a rise of between 0.6 to 1.0 degrees Fahrenheit and a two-inch increase in annual rainfall from previous 30-year averages.
Extreme Heat Trends: The past decade has seen a dramatic upsurge in days with temperatures exceeding 95°F. Montgomery County, for instance, experienced over 500 such days, marking a significant increase from the previous decade.
Urban Heat Islands: Certain areas, especially urban zones with dense infrastructure, tend to trap more heat, making them hotter than surrounding regions. Known as "heat islands," these zones exacerbate the effects of rising temperatures. Houston ranks fourth nationwide in terms of urban heat island intensity. Significantly, the neighborhoods most affected by high nighttime temperatures (which have the greatest health impacts) are often low-income communities and communities of color.
Climate Change Impacts and Mitigations
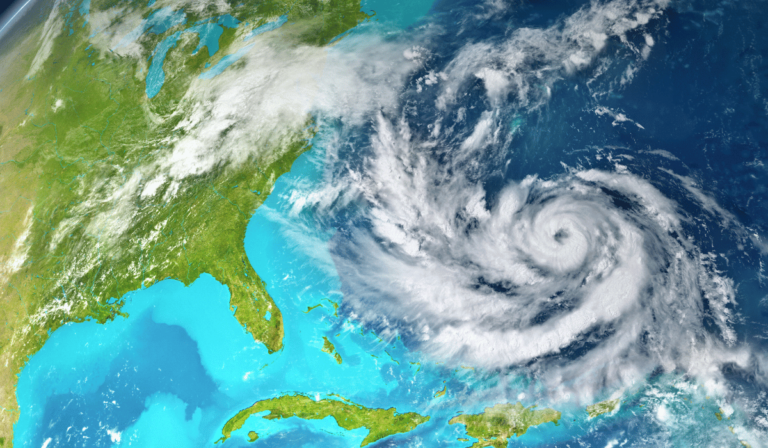
Understanding Climate Change: Human-caused greenhouse gas emissions have led to a phenomenon known as climate change, resulting in rising global temperatures. This intensifies various weather events and impacts such as storms, heatwaves, and heavy precipitation.
Effects on Precipitation: Since 1980, 12 rain events not associated with hurricanes or tropical storms have been declared disasters by FEMA. Climate change amplifies the intensity of these rainstorms, as a warmer atmosphere can hold and then release more water vapor.
Mitigation Measures: With the increased likelihood of intense rainstorms and flooding, local authorities are likely to look into building reservoirs and retention ponds as potential flood mitigation measures. Mobile homeowners need to be aware of these initiatives and their implications.
Flooding and Intense Rainstorms
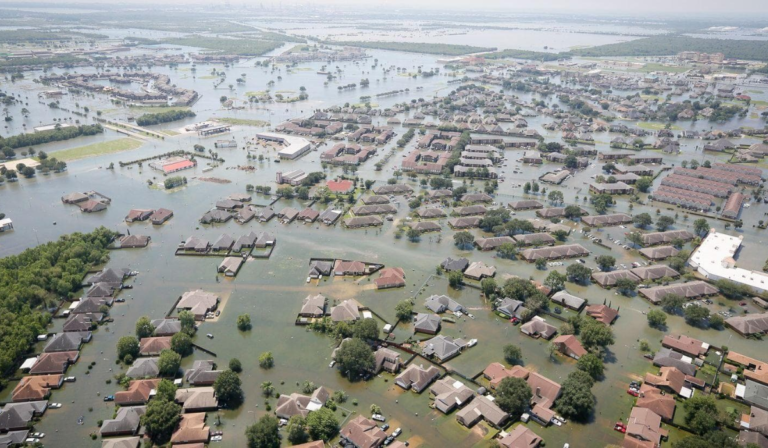
History & Projections: Over the past 41 years, the Houston region has experienced 26 federally declared disasters, with a significant portion of these being related to flooding. By 2050, over 350,000 properties are expected to face a "substantial" risk of flooding.
Flood Zones: Current FEMA maps identify properties based on flood risks: 1% annual chance of flooding (100-year flood) and 0.2% annual chance (500-year flood). However, real-life incidents have shown that flooding often surpasses these designated "high-risk" zones. In fact, more than 322,000 residential properties are situated in areas prone to flooding.
Communities at Risk: Research has indicated that communities predominantly comprising low-income and non-white residents are particularly vulnerable to flooding. Discriminatory housing policies in the past have led these groups to reside on low-lying lands with inadequate flood mitigation measures.
Given the diverse and intensifying weather risks in Houston, mobile homeowners should prioritize comprehensive insurance coverage. This coverage should encompass protection against flood damages (even if located outside traditional high-risk flood zones), heat-related damages, and potential impacts from intensified rainstorms and related mitigation measures.
We do insurance better. And here’s how.
- Save an average of $250 per year
- File a claim in 3 minutes
- Easily manage your policy online
- Skip the faxing, long paperwork, and unnecessary phone calls
- Get support from an American-based team
Are you in Houston, TX, looking for mobile home insurance
Choice of 6 insurance coverage in Houston, TX.
Identity Theft Coverage:
What it is: Protection against the financial fallout of identity theft, often covering expenses like legal fees or lost wages.
Why it's needed: With the rise in digital transactions and online activities, identity theft is a growing concern.
Military Personnel:
What it is: Protects against personal property loss for military members when deployed.
Why it's needed: Offers peace of mind to those serving their country, ensuring their property is safe.
Disappearing Deductibles:
What it is: Deductible decreases for each claim-free year.
Why it's needed: Rewards homeowners for not filing claims and provides financial benefits over time.
Extended Replacement Cost Coverage:
What it is: Boosts the limits of dwelling coverage, ensuring homes are rebuilt using similar materials.
Why it's needed: Protects against escalating building costs, ensuring homes are fully restored.
Scheduled Personal Property Coverage:
What it is: Increases the coverage amount for specific, valuable personal property items.
Why it's needed: Standard policies might not fully cover high-value items. This customization ensures adequate coverage.
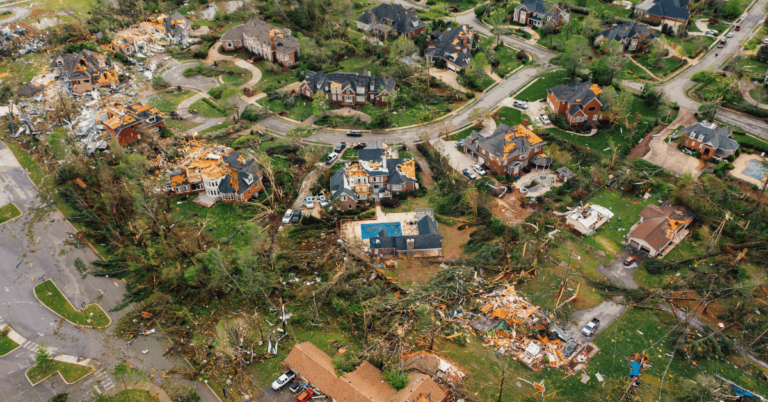
Weather/Natural Risks:
What it is: Protection against damages from weather events like tornadoes, hurricanes, hail, and more.
Why it's needed: Mobile homes can be especially vulnerable to severe weather events. This coverage offers peace of mind in volatile climates.
Mobile Home Facts : Texas
Treatment of Manufactured Home as Real Property:
- Once a “real property election” for a manufactured home is completed, the home is deemed as real property.
- This status remains unless the home is moved, the election changes, or the property’s use alters.
- Once a statement of ownership and location is given by the department, it’s final. Changes can only be made if all parties agree, or specific procedures are followed.
- If taking responsibility for a Statement of Ownership, ensure all housing department steps are followed, including necessary notifications.
According to the Texas Underwriting Manual TX: 12.24:
- 12.24.3: Any manufactured housing unit on the property isn’t included in the land described in this commitment or policy.
- 12.24.4: Upon a lender’s request and payment as specified in R-11(e), the T-31 and/or T-31.1 Endorsements can be issued; T-31.1 can be given to both the owner and the lender.
Learn about Texas Homeowner Assistance: Two Vital Programs!
Texas residents who are struggling with home-related expenses have two vital assistance programs available: the Texas Homeowner Assistance Program due to the COVID-19 pandemic and the Homeowner Assistance Program (HAP) following Hurricane Harvey.
Treatment of Manufactured Home as Real Property:
Purpose: Support homeowners impacted by Hurricane Harvey to repair, rebuild, and enhance their homes.
Services Offered: Financial support for affected homeowners.
Homeowner Assistance Program (HAP):
Purpose: Support homeowners impacted by Hurricane Harvey to repair, rebuild, and enhance their homes.
Services Offered: Home repairs and rehabilitation I Home reconstruction I Enhancements for better resilience against natural disasters I Elevating homes above flood levels along with reconstruction aid I Temporary relocation aid
Residents are encouraged to assess their eligibility and take advantage of these programs to secure and improve their homes.
The Texas Coastal Insurance Pool (TCIP), formerly known as the Texas Windstorm Insurance Association (TWIA), is a vital insurance entity designed to protect homeowners in the Texas coastal regions. Established in the face of limited private insurance options, the TCIP provides wind and hail coverage to properties located in certain parts of Texas’s seacoast territory.
Texas Coastal Property Insurance Pool Programs!
Key Features:
Rates:
Inland of the Intracoastal Canal $2.50 per $100 coverage 42 Effective October 1, 2008 Seaward of the Intracoastal Canal $5.00 per $100 coverage
Eligibility for TWIA:
A mobile home located in a designated catastrophe area that meets the following criteria is eligible to be insured under the T.W.I.A. Dwelling Policy with Form No. TWIA-411, Conversion to TWIA Manufactured Home Policy attached to the policy.
The mobile home complies with the definition of manufactured home under the rules and regulations of the Texas Department of Housing and Community Affairs (TDHCA). Criteria 2 The mobile home is occupied solely as a one or two family residence. Criteria 3Additions to Mobile Homes:
- A site-built addition attached to a mobile home will rate as part of the mobile home.
- A building certification from the Texas Department of Insurance is required for the site-built addition.
- Separate structures (not physically attached to the mobile home) are not eligible for insurance under the T.W.I.A. Dwelling Policy with Form No. TWIA411, Conversion to TWIA Manufactured Home Policy attached to the policy. Refer to eligibility requirements for insurance under the Association’s Dwelling Policy.
Deductibles:
- The following deductibles are mandatory under the T.W.I.A. Dwelling Policy with Form No. TWIA-411, Conversion to TWIA Manufactured Home Policy attached to the policy. a. Homes located inland of the Intracoastal Canal: 1% of limit of liability with a $250 minimum (TWIA Form No. 570) b. Homes located seaward of the Intracoastal Canal: 2% of the limit of liability with a $250 minimum (TWIA Form No. 575)
- Deductibles apply separately to the home and household goods items on the policy.
Limit of Liability:
The maximum limit of liability for a mobile home, including any site-built additions attached to the home, and household goods is $84,000.
Policy Forms & Endorsements:
The following policy form is to be used: T.W.I.A. Dwelling Policy with Form No. TWIA-411, Conversion to TWIA Manufactured Home Policy attached to the policy
Know Your Rights!
- Texas Tenant Advisor
- Texas Law Help – Manufactured Housing Owner’s Rights
- Property Code TITLE 8. Landlord and Tenant Chapter 94. Manufactured Home Tenancies
- Property Code TITLE 8. Landlord and Tenant Chapter 92. Manufactured Home Tenancies
- Landlords and Tenants Guide for Manufactured Home Communities
- Texas Manufactured Housing Standards Act
- Legal Q&A By Sarah Tompkins, TML Legal Counsel
- Texas Law Help – What To Know Before You Buy a Manufactured/Mobile Home
- Homeowner Assistance Program
- Manufactured Housing Single-Trip Permits
- Mobile Home Insurance in Texas
- Texas Department of Insurance – Consumer Guides: Homeowner’s Insurance Guide
- Consumer Bill of Rights
- Texas Windstorm Insurance Association
- Texas Windstorm Help Guide
- Texas Law Help – Manufactured Housing and Disasters
Additional Policy Riders for Mobile Home Insurance in Texas:
Adding policy options to a basic insurance plan is a common practice in the mobile home insurance industry. While the events covered in mobile home policies are similar across all states, additional coverage options, known as add-ons, endorsements, and riders, may vary depending on your location and insurance provider. Each of these options comes at an additional cost that can be customized according to your needs.
Provides protection against flood-related damages, excluding waterline or sewer backups. Average annual cost: $700. Earthquake InsuranceAdding any rider will increase your premiums, influenced by location, risk profile, chosen coverage, and deductible. Riders can be added during initial policy purchase, at renewal, or anytime during the policy period. Some carriers might not offer all endorsements, so shopping around might be necessary.
Finding the Best Mobile Home Insurance in
Houston, TX
It's essential to compare quotes from various insurance providers and work with local agencies that understand Houston's specific risks. You also need to be vocal about being able to customize your policy to cover specific needs like monsoon or dust storm damages. Always remember to ask about any available discounts that you may be eligible for!
- Description: This rider provides coverage for damages specifically caused by windstorms and hail.
- Importance: Given Houston’s vulnerability to hurricanes and tropical storms, ensuring you’re protected against wind and hail damage is critical. Repairing such damages without insurance can be exorbitant.
- Description: Protection against water damage caused by flooding, whether from storm surges, heavy rainfalls, or other sources.
- Importance: Houston’s flat terrain and susceptibility to heavy rains make it prone to flooding. Standard policies usually exclude flood damage, making this coverage essential for mobile homeowners in the region.
- Description: Covers damage resulting from sewers or drains backing up.
- Importance: Backed up sewers can cause extensive water damage, often when least expected. This add-on ensures you’re covered for such events.
Extended Coverage for Personal Belongings:
- Description: Increases the standard limit of coverage for personal belongings.
- Importance: If you have items that exceed the standard policy limits, this add-on ensures they’re fully protected.
- Description: Provides assistance and financial coverage to restore your identity if it’s stolen.
- Importance: In our digital age, identity theft is a growing concern. This coverage provides peace of mind and necessary resources in case of such events.
Credit Card and Check Forgery Coverage:
- Description: Offers protection against financial losses due to fraud or unauthorized use of checks or credit cards.
- Importance: Financial fraud can be distressing and costly. This coverage offers an extra layer of financial security.