
Insurance guides
Protecting Your Manufactured Home in Corpus Christi, TX.
Disclaimer: Data Accuracy and Sources
The data in the Covertree Resources section is from publicly available sources last updated in December 2022. We provide source links for verification. However, we can’t guarantee accuracy. Rely on this data at your own discretion. For specific advice, consult professionals.
Known for its eleven pristine beaches, two marinas, and boasting an enviable average temperature of about seventy degrees, Corpus Christi beckons millions of vacationers every year. These sun-chasers often find themselves awestruck by the vast stretches of undeveloped barrier island at the Padre Island National Seashore and the 1.75-mile scenic Corpus Christi Seawall that offers unparalleled views of the city’s marina, restaurants, and the poignant Selena Memorial.
But there’s more to Corpus Christi than just its natural allure. The city is a tapestry of diverse districts, from defense bases and oil professionals to surfers and a thriving Hispanic population. This diversity is its strength, fostering a community that champions identity, self-expression, and unity. It’s a place where history floats, quite literally, in the form of the USS Lexington Museum, and art and culture thrive, evident in places like the Art Museum of South Texas and the Harbor Playhouse. Educational institutions like Texas A&M University–Corpus Christi, perched on Ward Island, further underline the city’s commitment to progress and growth.
Corpus Christi’s history is a testament to its resilience and adaptability. Originally a humble frontier trading post established by Colonel Henry Lawrence Kinney in the late 1830s, the city evolved into an important military point, a safe haven during wartime, and eventually, a vital economic and cultural hub. The spirit of the city’s first mayor, Benjamin F. Neal, lives on, as modern-day Corpus Christi operates under a home-rule government, striving for excellence in public service, safety, and community welfare. Sports enthusiasts, nature lovers, art connoisseurs, and history buffs alike find their sanctuary here. From the weekly sailboat races by Midget Ocean Racing Fleet (M.O.R.F.) to the annual Texas Jazz Festival, from the fascinating Texas Surf Museum to the enchanting South Texas Botanical Garden & Nature Center, there’s a slice of Corpus Christi for every soul.
A testament to its enduring spirit and commitment to its residents, Corpus Christi has established state-of-the-art communication systems, top-tier emergency services, and progressive community programs. The city takes pride in not only its past but also in its drive towards a brighter, more inclusive future.
In Corpus Christi, every street echoes with stories of the past, every wave brings promises of the future, and every sunset is an invitation to discover the city’s magic all over again. Whether you’re retracing the steps of Spanish explorers, basking in the melodies of world-class jazz, or simply letting the Gulf winds guide you to your next adventure, Corpus Christi welcomes you with open arms and a warm heart.Understanding Mobile Home Insurance In Texas.
Do I Need Mobile Home Insurance in Texas?
Do I Need Mobile Home Insurance in Texas?
- Optional, but often required by lenders and mobile home communities.
- Lenders can’t mandate coverage that surpasses home and content replacement value.
- Strongly recommended for financial protection against damages.
Texas Mobile Home Insurance Costs Explained
Texas Mobile Home Insurance Costs Explained
Mobile home insurance is essential for safeguarding your most valuable asset. Prices in Texas typically range from $250 to $1,300 annually, influenced by various factors. Deciding between actual cash value and replacement cost coverage will also impact both premiums and compensation amounts in case of a claim.
Insurance rates are influenced by:
Insurance rates are influenced by:
- Geographic area (land value, crime rate, and environmental threats).
- Home’s value, size, and location.
- Home’s age.
- Chosen liability coverage.
- Desired personal property coverage amount.
- Selected deductible.
- Actual Cash Value: Compensates the current value of the home, accounting for depreciation. *
- Replacement Cost: Covers the cost of a new, similar home regardless of the original home’s age or previous value. **
* e.g. A five-year-old home bought for $50,000 but now worth $35,000 will be compensated at $35,000.
** Typically has higher premiums but offers more compensation during a claim.
Unique Considerations for Texas Mobile Home Insurance!
Unique Considerations for Texas Mobile Home Insurance!
- Wind and hail coverage may be excluded for homes near the coast.
- Purchase flood insurance via the National Flood Insurance Program if difficult to find in the private market.
- For wind and hail coverage, consider Texas Windstorm Insurance Association (TWIA).
Mobile Home Insurance Coverage in Texas:
Mobile Home Insurance Coverage in Texas:
- Dwelling coverage: Protection for permanent structures attached to the home.
- Personal property: Covers belongings if damaged or stolen.
- Liability protection: Provides financial protection in case a guest is injured on your property.
- Other structures: Coverage for free-standing structures on your property, e.g., sheds or fences.
- Additional living expenses: Covers costs if home becomes uninhabitable due to a covered loss.
Filing a Mobile Home Insurance Claim in Texas:
Filing a Mobile Home Insurance Claim in Texas:
- Insurance companies must acknowledge the claim within 15 days.
- Companies have 15 business days to accept or deny a claim, with potential for extensions in the event of major disasters.
- Possible 45-day decision timeframe if reasons are provided for delay.
- Failure to adhere to deadlines could result in the company being sued for the claim amount, interest, and legal fees.
Tips for Purchasing Mobile Home Insurance in Texas:
Tips for Purchasing Mobile Home Insurance in Texas:
- Mobile home insurance is often pricier than standard homeowners insurance.
- Best way to get affordable rates is to compare quotes from various companies.
- Online quotes might not be available; be prepared to call companies.
- Customizable policy options available to cater to individual needs.
Remember, while insurance might seem optional, it provides invaluable peace of mind against potential financial setbacks.
Choosing the Ideal Texas Homeowners Insurance Policy:
Choosing the Ideal Texas Homeowners Insurance Policy:
The apt insurance policy largely hinges on your home type, repair or rebuilding costs, and the worth of your belongings. It’s often a smart move to opt for the most robust protection within your budget. This is especially true if you haven’t set aside a significant emergency fund. Though a comprehensive policy with a lower deductible might require higher premiums, it ensures quick recovery after a substantial loss.
As your savings grow, you might consider increasing your deductible to decrease your premium. But here’s a pro tip: sometimes, a $1,000 deductible isn’t much pricier than a $5,000 one. In such instances, the minimal extra expense can prove invaluable in the event of a large claim.
The location of your mobile home, particularly the zip code in Texas, is a significant factor.
The location of your mobile home, particularly the zip code in Texas, is a significant factor.
You Need: The HO-7: Texas Mobile Home Form
You Need: The HO-7: Texas Mobile Home Form
- For Texas residents who own a mobile home, the HO-7 insurance form is crucial.
- This insurance covers both your dwelling and personal property.
- The HO-7 offers comparable coverage to the HO-3 policy.
- One thing to remember: if you plan on moving your mobile home, the HO-7 doesn’t always cover it while in transit. You may need to consider supplemental insurance in such cases.
What Does an HO-7 Policy Cover?
Type of Homes: Mobile or manufactured homes (trailers, single/double-wide mobile homes, RVs, modular homes, etc.).
Property (Dwelling & Other Structures)
Contents (Personal Property)
Dwelling & Other Structures
Personal Property
Valuable Items
Liability
Loss of Use
Medical Payments
What Does an HO-7 Policy NOT Cover?
Personal property damage that doesn't fit the named perils. Exclusions include:
- Floods
- Hurricanes
- Mold (Limited Coverage Might be Possible to Add)
- Earthquakes (Separate Policy Might be Available)
- Vandalism to Vacant Dwellings
- Wear and Tear
- Damage From Pets
- Intentional Acts
- Neglect
- Government Actions
Understand The HO-3: Texas Special Form
The HO-3 policy is the predominant homeowners insurance in Texas. It offers open-peril coverage for homes and related structures, covering all damages unless specifically excluded. Exclusions typically include:
- Earthquakes
- Floods
- Damage from insects & vermin
- Wear, neglect, or intentional damage
- Wind/hail damage to trees
- Vacancies, continuous water leaks
- Sewer backups, acts of war
- Certain mold cases
Additional Insurance Policy Options:
Even if you’ve chosen the HO-7 or another base form for your policy, you might still want to contemplate additional coverage for specific scenarios. Here are some prevalent options:
Texas DP-1 Insurance
Texas DP-3 Insurance
Personal Umbrella Policy
Scheduled Personal Property Coverage
Water Backup Coverage
Unmitigated Disasters
Choosing the Right Mobile Home Insurance for Corpus Christi, TX.
Heatwaves and the Rising Demand for Cooling
>
Overview:
Corpus Christi is witnessing an escalating risk from extreme heat. With "feels like" temperatures on the rise, the region faces an increasing likelihood of heat waves. This year alone, the chances of experiencing a 3+ day heat wave stand at 45%, and in 30 years, this probability nearly doubles to 88%. As the temperatures soar, residents are inclined to rely more on air conditioning, with the city anticipating an increase in energy consumption on 299 days annually. This number is expected to climb further, to 308 days per year within 30 years, culminating in an 8.20% boost in Corpus Christi's electricity usage for cooling purposes.Implications for Mobile Home Owners and Insurance:
The unique construction and insulation properties of mobile homes can make them particularly susceptible to heat. As such, mobile home owners might experience increased energy costs due to heavier reliance on cooling systems. Additionally, insurance premiums may rise, reflecting the augmented risks of heat-related damages, such as warped or damaged infrastructure. Mobile home owners should also be vigilant about health risks, such as heat stroke, fatigue, and dehydration, which are particularly hazardous in confined spaces that mobile homes often present.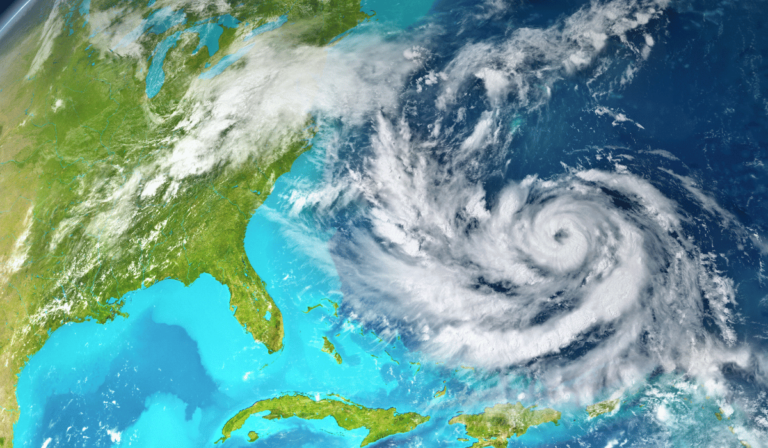
Sea-Level Rise and Hurricane Intensity
Overview:
Corpus Christi's coastal location renders it especially vulnerable to sea-level rise, a phenomenon aggravated by geologic subsidence and oil extraction. Historical records indicate that the region has already witnessed 1.7 feet of sea-level rise in the last 100 years. Predictions suggest an additional rise of about 2.6 feet by the 2080s. Compounding this risk is the forecasted intensification of hurricanes due to warmer ocean waters. Hurricanes are anticipated to bring with them increased wind speeds and rainfall, with flood levels possibly soaring by up to 100% by the 2080s.Implications for Mobile Home Owners and Insurance:
Mobile homes, given their light construction and grounding mechanisms, are inherently at risk from strong wind events and flooding. With rising sea levels and the prospect of more intense hurricanes, mobile home parks situated near the coast or in flood-prone zones could face severe damages or complete destruction. Mobile home owners are advised to reassess their current coverage, considering flood insurance and windstorm provisions, to ensure they are adequately protected.
Extreme Droughts and Power Outages
Overview:
Corpus Christi has observed extreme and severe droughts, which can stress local resources and elevate the risk of wildfires. Moreover, the city has recently experienced power outages due to adverse weather conditions, which can compromise essential services and disrupt daily life.Implications for Mobile Home Owners and Insurance:
Drought conditions can heighten the risk of fires, a significant concern for mobile home communities due to their proximity to one another and the materials often used in their construction. Power outages can impact mobile home residents by disabling vital systems like air conditioning or heating, which are crucial for comfort and safety in extreme weather conditions.We do insurance better. And here’s how.
- Save an average of $250 per year
- File a claim in 3 minutes
- Easily manage your policy online
- Skip the faxing, long paperwork, and unnecessary phone calls
- Get support from an American-based team
Are you in Corpus Christi, TX, looking for mobile home insurance
Choice of 6 insurance coverage in Corpus Christi, TX.
Enhanced Dwelling Protection:
What it is: Provides added coverage for rebuilding expenses that go over the policy's stated limit.
Why it's needed: Rebuilding costs can escalate due to factors like increased materials prices or changes in building codes. This ensures full coverage.
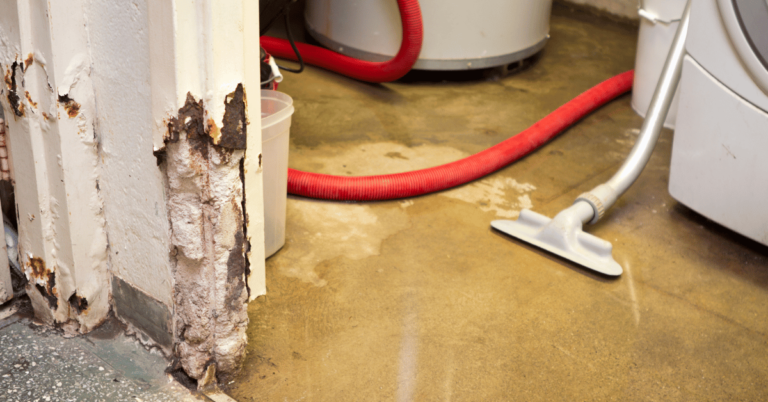
Foundation and Water Damage Coverage:
What it is: Specifically covers repairs linked to foundation or water damage.
Why it's needed: Foundation repairs are costly, and water damage can lead to further complications like mold. This add-on provides targeted protection.
Extended Coverage on Jewelry and Furs:
What it is: Additional insurance for valuable items like jewelry and furs, going beyond standard coverage limits.
Why it's needed: Valuable items can have costs that exceed standard policy limits, making this essential for full compensation.
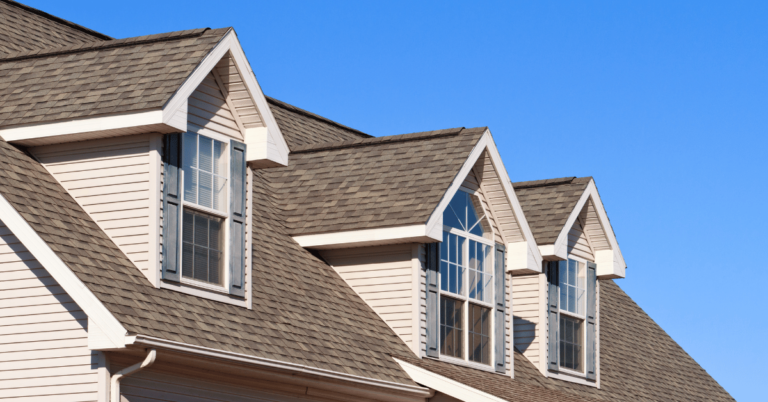
Matching Siding/Roof:
What it is: Guarantees that if part of your siding or roof is damaged, the replaced section will match the existing, undamaged areas.
Why it's needed: Aesthetic consistency is important for home value, and mismatched repairs can be visually unappealing.
Pest Damage:
What it is: Coverage against damages caused by pests like termites, rodents, etc.
Why it's needed: Pest damage can be expensive to repair and isn't always covered in standard policies.
High Deductible Waiver for Catastrophic Ground Cover Collapse:
What it is: The deductible is waived if there's a catastrophic ground cover collapse.
Why it's needed: In areas prone to such events, this can provide significant financial relief.
Mobile Home Facts : Texas
Treatment of Manufactured Home as Real Property:
- Once a “real property election” for a manufactured home is completed, the home is deemed as real property.
- This status remains unless the home is moved, the election changes, or the property’s use alters.
- Once a statement of ownership and location is given by the department, it’s final. Changes can only be made if all parties agree, or specific procedures are followed.
- If taking responsibility for a Statement of Ownership, ensure all housing department steps are followed, including necessary notifications.
According to the Texas Underwriting Manual TX: 12.24:
- 12.24.3: Any manufactured housing unit on the property isn’t included in the land described in this commitment or policy.
- 12.24.4: Upon a lender’s request and payment as specified in R-11(e), the T-31 and/or T-31.1 Endorsements can be issued; T-31.1 can be given to both the owner and the lender.
Learn about Texas Homeowner Assistance: Two Vital Programs!
Texas residents who are struggling with home-related expenses have two vital assistance programs available: the Texas Homeowner Assistance Program due to the COVID-19 pandemic and the Homeowner Assistance Program (HAP) following Hurricane Harvey.
Treatment of Manufactured Home as Real Property:
Purpose: Support homeowners impacted by Hurricane Harvey to repair, rebuild, and enhance their homes.
Services Offered: Financial support for affected homeowners.
Homeowner Assistance Program (HAP):
Purpose: Support homeowners impacted by Hurricane Harvey to repair, rebuild, and enhance their homes.
Services Offered: Home repairs and rehabilitation I Home reconstruction I Enhancements for better resilience against natural disasters I Elevating homes above flood levels along with reconstruction aid I Temporary relocation aid
Residents are encouraged to assess their eligibility and take advantage of these programs to secure and improve their homes.
The Texas Coastal Insurance Pool (TCIP), formerly known as the Texas Windstorm Insurance Association (TWIA), is a vital insurance entity designed to protect homeowners in the Texas coastal regions. Established in the face of limited private insurance options, the TCIP provides wind and hail coverage to properties located in certain parts of Texas’s seacoast territory.
Texas Coastal Property Insurance Pool Programs!
Key Features:
Rates:
Inland of the Intracoastal Canal $2.50 per $100 coverage 42 Effective October 1, 2008 Seaward of the Intracoastal Canal $5.00 per $100 coverage
Eligibility for TWIA:
A mobile home located in a designated catastrophe area that meets the following criteria is eligible to be insured under the T.W.I.A. Dwelling Policy with Form No. TWIA-411, Conversion to TWIA Manufactured Home Policy attached to the policy.
The mobile home complies with the definition of manufactured home under the rules and regulations of the Texas Department of Housing and Community Affairs (TDHCA). Criteria 2 The mobile home is occupied solely as a one or two family residence. Criteria 3Additions to Mobile Homes:
- A site-built addition attached to a mobile home will rate as part of the mobile home.
- A building certification from the Texas Department of Insurance is required for the site-built addition.
- Separate structures (not physically attached to the mobile home) are not eligible for insurance under the T.W.I.A. Dwelling Policy with Form No. TWIA411, Conversion to TWIA Manufactured Home Policy attached to the policy. Refer to eligibility requirements for insurance under the Association’s Dwelling Policy.
Deductibles:
- The following deductibles are mandatory under the T.W.I.A. Dwelling Policy with Form No. TWIA-411, Conversion to TWIA Manufactured Home Policy attached to the policy. a. Homes located inland of the Intracoastal Canal: 1% of limit of liability with a $250 minimum (TWIA Form No. 570) b. Homes located seaward of the Intracoastal Canal: 2% of the limit of liability with a $250 minimum (TWIA Form No. 575)
- Deductibles apply separately to the home and household goods items on the policy.
Limit of Liability:
The maximum limit of liability for a mobile home, including any site-built additions attached to the home, and household goods is $84,000.
Policy Forms & Endorsements:
The following policy form is to be used: T.W.I.A. Dwelling Policy with Form No. TWIA-411, Conversion to TWIA Manufactured Home Policy attached to the policy
Know Your Rights!
- Texas Tenant Advisor
- Texas Law Help – Manufactured Housing Owner’s Rights
- Property Code TITLE 8. Landlord and Tenant Chapter 94. Manufactured Home Tenancies
- Property Code TITLE 8. Landlord and Tenant Chapter 92. Manufactured Home Tenancies
- Landlords and Tenants Guide for Manufactured Home Communities
- Texas Manufactured Housing Standards Act
- Legal Q&A By Sarah Tompkins, TML Legal Counsel
- Texas Law Help – What To Know Before You Buy a Manufactured/Mobile Home
- Homeowner Assistance Program
- Manufactured Housing Single-Trip Permits
- Mobile Home Insurance in Texas
- Texas Department of Insurance – Consumer Guides: Homeowner’s Insurance Guide
- Consumer Bill of Rights
- Texas Windstorm Insurance Association
- Texas Windstorm Help Guide
- Texas Law Help – Manufactured Housing and Disasters
Additional Policy Riders for Mobile Home Insurance in Texas:
Adding policy options to a basic insurance plan is a common practice in the mobile home insurance industry. While the events covered in mobile home policies are similar across all states, additional coverage options, known as add-ons, endorsements, and riders, may vary depending on your location and insurance provider. Each of these options comes at an additional cost that can be customized according to your needs.
Provides protection against flood-related damages, excluding waterline or sewer backups. Average annual cost: $700. Earthquake InsuranceAdding any rider will increase your premiums, influenced by location, risk profile, chosen coverage, and deductible. Riders can be added during initial policy purchase, at renewal, or anytime during the policy period. Some carriers might not offer all endorsements, so shopping around might be necessary.
References:
References:
References: